Who lends to India: the banks
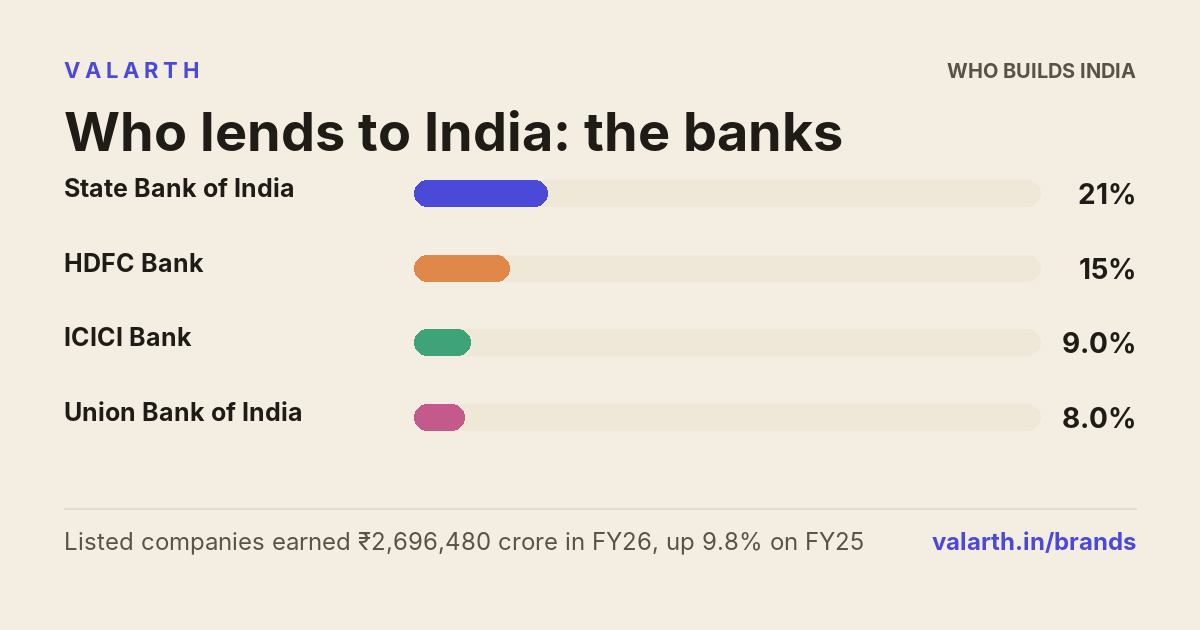
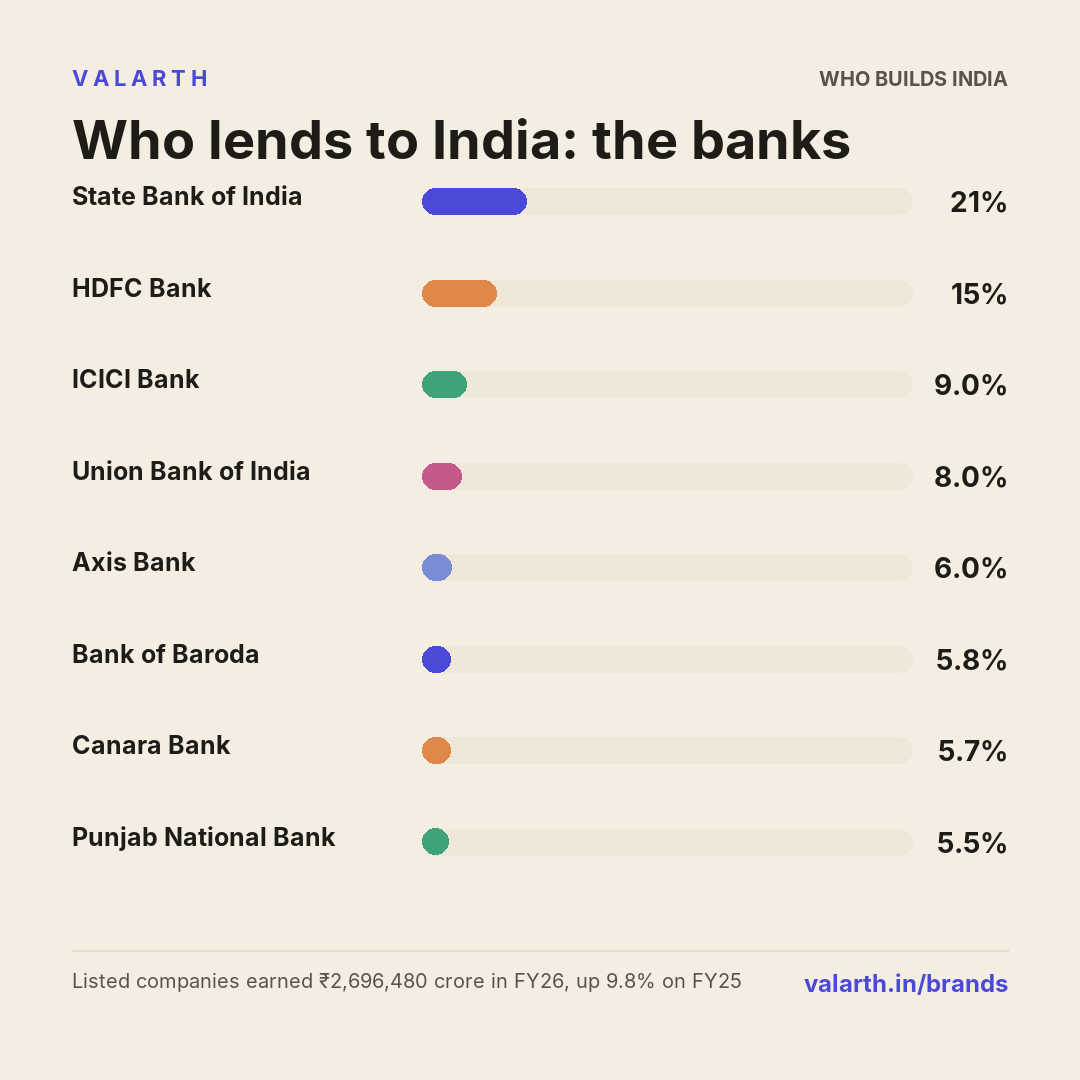
24 listed companies earned ₹2,696,480 crore from banking in FY26, up 9.8% on FY25. State Bank of India earned the most, 21.2% of it. Karur Vysya Bank Ltd earned the most on each rupee of sales: 33.6%.
Banks earn mainly from interest on the loans they make to households and businesses, from fees, and from government bonds and other investments in their treasury books. The 24 listed banks on this page reported ₹26,96,480 crore of revenue from banking in FY26. These figures cover only listed banks. Unlisted lenders, such as foreign banks' Indian branches and the regional rural banks, are not counted. State Bank of India took 21.2% of the listed total, HDFC Bank 15.1% and ICICI Bank 9.0%. The 11 banks the government owns directly, from SBI down to UCO Bank, add up to 56.7%. IDBI Bank, owned by the government and LIC together, adds another 1.3%.
The page shows the listed total up 9.8% on FY25. About half of that rise comes from how two banks' segment figures were recorded. Union Bank's FY26 figure counts two segments twice, and Bank of India's FY25 figure leaves out its treasury segment. Corrected for both, the listed total grew about 5%, close to the large banks: SBI up 5.6%, HDFC Bank 5.5%, ICICI Bank 4.8%. It was a year of falling interest rates. The RBI cut its policy rate by 1.25 percentage points between February and December 2025, and loan rates fell faster than deposit rates.
Profit is less evenly spread than revenue. ICICI Bank, Kotak Mahindra, IDBI Bank and Karur Vysya keep 27.5% to 33.6% of revenue as profit. Bandhan, RBL and IDFC First keep 3.9% to 6.0%. For the banking system as a whole, the RBI says deposits grew 11.5% in FY26.
The brands, and who owns them
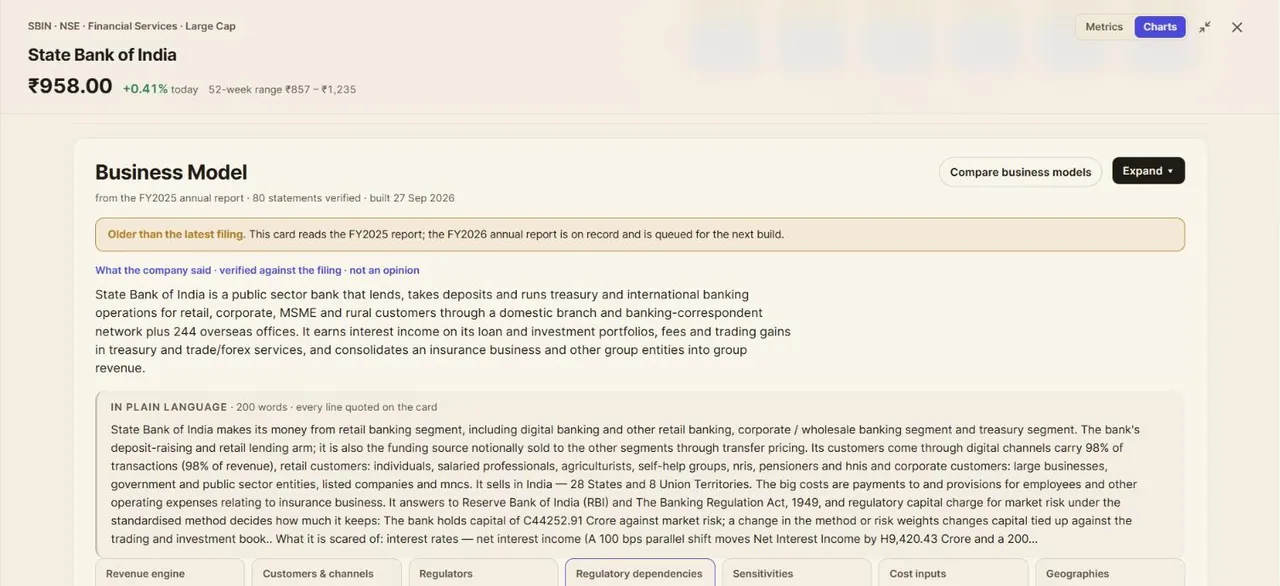
Mobile Omni Neo is Bank of India's; INDIE, IndusMobile, INDIE For Business, Indus Care and others are IndusInd Bank Ltd's; IRIS Biz, IRIS Biz by YES BANK, IRIS by YES BANK, YES Business are Yes Bank Ltd's; IDBI Advantage Savings Accounts, Utsav Fixed Deposits, IDBI Sameep are IDBI Bank Ltd's; AU0101 is AU Small Finance Bank Ltd's; RBL MyBank, RBL Cares Chatbot are RBL Bank Ltd's; KVB DLite is Karur Vysya Bank Ltd's. Brands are read from each company's filings and checked against a public source.
Who sells the most
State Bank of India had 21.2% of the listed companies' revenue from banking here, 1.4 times as much as HDFC Bank Ltd, the next largest. The two together sold 36%; the other 22 the rest.
What the figures show
Two big jumps in growth come from how the data was recorded
Union Bank shows 70.7% growth, and its banking revenue comes to 168% of the whole company's. Its FY26 segment report, which sits behind this page, lists Retail (₹47,574 crore) and Corporate/Wholesale (₹44,379 crore) twice. Taking them out once: ₹2,15,758 − 47,574 − 44,379 = about ₹1,23,805 crore, slightly below FY25's ₹1,26,427 crore. Bank of India's FY25 figure of ₹58,392 crore is just Retail (₹31,053 crore) plus Wholesale (₹27,339 crore) from its segment report. Adding Treasury (₹22,736 crore) gives ₹81,128 crore, so on the same basis FY26's ₹84,877 crore is up about 4.6%, not 45.4%. These corrections are our estimates from the banks' segment figures, not numbers the page shows.
Corrected, the listed total grew about 5%, not 9.8%
The FY25 figures on the page add up to ₹24,56,918 crore, and FY26 to ₹26,96,480 crore (up 9.8%). Removing Union Bank's double count (₹91,953 crore) gives FY26 of about ₹26,04,527 crore. Adding Bank of India's missing FY25 treasury (₹22,736 crore) gives FY25 of about ₹24,79,654 crore. That works out to growth of about 5.0%. With Union Bank corrected, the listed total is also smaller, so every bank's share would be slightly higher than the page shows.
The top three earn more than their size
SBI, HDFC Bank and ICICI Bank have 45.3% of listed revenue and 48.0% of listed profit. ICICI Bank does the most with what it has: 9.0% of revenue but 12.3% of profit, and a return on assets of 2.7%, the highest on the page. SBI is the other way round: 21.2% of revenue but 18.2% of profit, with a return on assets of 1.3%.
Rate cuts hit the margins of some banks
Kotak's margin fell from 34.4% to 28.5%, Axis Bank's from 23.4% to 19.9%, and Bank of Baroda's from 22.5% to 20.4%. Many loans in India are linked directly to the RBI's repo rate (the rate at which it lends to banks), so their rates fall as soon as the RBI cuts. Deposit rates take longer to come down. Fitch expected this to squeeze bank margins in FY26. Press reports on Kotak's results said its net interest margin (interest earned minus interest paid, as a share of loans and investments) fell to 4.67% in the March quarter from 4.97% a year earlier, and full-year profit fell about 15%. Several government banks moved the other way: Bank of Maharashtra rose from 20.1% to 23.8%, Indian Overseas
Small-loan stress shows at Bandhan
Bandhan's margin fell from 13.3% to 5.1% and its revenue dropped 2.5%. Bandhan and IndusInd (down 5.1%) are the only banks on the page whose revenue fell. Retail is 79% of Bandhan's revenue, the highest share of any bank here. Much of that is microfinance: small loans, mostly to women in villages. Press reports put Bandhan's FY26 profit down 55%, and connect its weak quarters to unpaid microfinance loans. IDFC First (3.9%) and RBL (6.0%) also keep little of their revenue as profit.
Fastest growth came from smaller banks
Leaving out the two bookkeeping cases, the fastest growth came from AU Small Finance Bank (16.3%), Bank of Maharashtra (15.9%), Karur Vysya (14.4%), Indian Overseas Bank (13.9%) and IDFC First (11.5%). Each has less than 2% of the listed total. The three largest banks grew between 4.8% and 5.6%. Treasury income (from government bonds and other investments) is a large part of revenue at some banks: 35% at ICICI Bank, 32% at Central Bank and 30% at PNB, against 14% at HDFC Bank and Axis Bank.
How the sales have grown, and who sold them
The listed companies here earned ₹26.96 lakh Cr from banking in FY26, up from ₹24.57 lakh Cr in FY25.
Who earns the most on each rupee
Operating profit before interest and tax, as a share of revenue from banking. State Bank of India earned 17.3% on its sales in FY26, against 18.0% in FY25. HDFC Bank Ltd earned 23.4% on its sales in FY26, against 23.5% in FY25. ICICI Bank Ltd earned 27.5% on its sales in FY26, against 27.4% in FY25. Union Bank of India earned 17.9% on its sales in FY26, against 17.7% in FY25. Axis Bank Ltd earned 19.9% on its sales in FY26, against 23.4% in FY25. Bank of Baroda earned 20.4% on its sales in FY26, against 22.5% in FY25.
The whole market, and what is changing
We found no official figure for the total revenue of all Indian banks, so listed revenue cannot be shown as a share of a revenue-based market. The RBI measures the system by deposits and loans. Its FY26 figures give deposit growth of 11.5% for all scheduled commercial banks (banks listed under the RBI Act, which includes unlisted and foreign banks). An RBI Bulletin table shows bank credit outstanding of about ₹2,13,61,435 crore at 31 March 2026, against ₹1,85,01,377 crore a year earlier. That is roughly 15.4% growth, our calculation from the table. Credit growing faster than deposits is why banks now lend out more of each rupee deposited. (source)
- Rates fell quickly. The RBI cut its repo rate from 6.5% to 5.5% between February and June 2025, and then to 5.25% in December 2025. Business Standard reported that private banks' net interest margin fell to 3.87% in the September 2025 quarter from 4.02%, and state-owned banks' to 2.71% from 2.81%. (source)
- Banks are lending out more of the money deposited with them. An RBI Bulletin, as reported by Millennium Post, says the credit-deposit ratio of scheduled commercial banks rose from 68.6% in September 2021 to 82.2% in March 2026. An EPW article gives 81.7% for March 2026. (source)
- Private banks are now raising deposits faster than government banks. RBI data reported by Business Standard show private banks' deposits up 13.8% and public sector banks' up 10.3% at the end of June 2026. (source)
The companies, and their brands
| Company and brands | Sales FY26 | Growth 1 yr | 3 yrs | 5 yrs | Margin | Profit share | Return on assets | P/E | ROE | Share price 1 yr |
|---|---|---|---|---|---|---|---|---|---|---|
| State Bank of India The country's largest lender, with ₹5,71,610 crore of banking revenue (21.2% of the listed total), up 5.6%. It keeps 17.3% as profit, less than most large peers. Retail banking is 45% of its revenue. Sells in 28 states and 29 countries; exports 0.0% of turnover |
₹571,610 Cr | +5.6% | — | — | 17.3% | 18.2% | 1.3% | 10.3 | 17.3% | +9.1% |
| HDFC Bank Ltd Second largest at ₹4,08,022 crore, up 5.5%. Its 23.4% margin and 2.2% return on assets give it 17.5% of listed profit, close to SBI's 18.2% on far less revenue. Retail is 51% of its revenue. Sells in 28 states and 6 countries; exports 0.0% of turnover |
₹408,022 Cr | +5.5% | — | — | 23.4% | 17.5% | 2.2% | 13.9 | 14.0% | -26.9% |
| ICICI Bank Ltd Third at ₹2,42,219 crore, and the most profitable of the top three: 27.5% margin and 2.7% return on assets. Treasury is 35% of its revenue, the highest share on the page. Sells in 35 states and 14 countries; exports 0.0% of turnover |
₹242,219 Cr | +4.8% | — | — | 27.5% | 12.3% | 2.7% | 17.4 | 16.1% | -1.7% |
| Union Bank of India The page's ₹2,15,758 crore counts two segments twice. Our estimate of the corrected FY26 revenue is about ₹1,23,805 crore, slightly below FY25's ₹1,26,427 crore, so the 70.7% growth shown is not real. |
₹215,758 Cr | +70.7% | — | — | 17.9% | 7.1% | — | 6.4 | 16.3% | +25.7% |
| Axis Bank Ltd ₹1,62,148 crore, up 4.2%. Its margin fell from 23.4% to 19.9%. It reports digital banking as a separate retail line, at 16% of revenue, next to 45% from other retail banking. Sells in 35 states and 2 countries; exports 0.0% of turnover |
₹162,148 Cr | +4.2% | — | — | 19.9% | 5.9% | 1.7% | 14.2 | 12.7% | +7.8% |
| Bank of Baroda ₹1,56,825 crore, up 2.6%. Its margin fell from 22.5% to 20.4%. Wholesale banking is 32% of revenue. Sells in 35 states and 15 countries; exports 0.0% of turnover |
₹156,825 Cr | +2.6% | — | — | 20.4% | 5.9% | 1.6% | 6.8 | 13.8% | -9.7% |
| Canara Bank ₹1,53,083 crore, up 8.0%, the fastest of the five largest government banks. Its margin is thin at 16.1%. Sells in 36 states and 4 countries; exports 0.0% of turnover |
₹153,083 Cr | +8.0% | — | — | 16.1% | 4.5% | 1.4% | 5.5 | 18.0% | -3.8% |
| Punjab National Bank ₹1,49,463 crore, up 6.4%, with a 22.9% margin. Corporate lending is its largest line at 38%, and treasury is 30% of revenue. Sells in 35 states and 1 countries; exports 0.0% of turnover |
₹149,463 Cr | +6.4% | — | — | 22.9% | 6.3% | 1.7% | 6.1 | 13.4% | +1.1% |
| Bank of India ₹84,877 crore. The 45.4% growth shown is because the FY25 figure leaves out treasury. Our estimate on the same basis is about 4.6%. Its margin improved from 15.8% to 19.7%. Mobile Omni Neo Sells in 36 states and 10 countries; exports 0.0% of turnover |
₹84,877 Cr | +45.4% | — | — | 19.7% | 3.1% | 1.5% | 5.2 | 14.0% | +8.1% |
| Kotak Mahindra Bank Ltd ₹69,751 crore, up 3.6%. Its margin of 28.5% is still among the highest on the page, but down from 34.4% as rate cuts squeezed its interest margin, according to press reports on its results. Sells in 30 states and 2 countries; exports 0.0% of turnover |
₹69,751 Cr | +3.6% | — | — | 28.5% | 3.7% | 1.8% | 21.5 | 11.1% | +2.0% |
| Indian Bank ₹57,241 crore, up 8.0%, with a 21.4% margin. It reports only two segments: retail 56% and corporate 44%. |
₹57,241 Cr | +8.0% | — | — | 21.4% | 2.3% | 1.8% | 8.9 | 18.2% | +9.6% |
| IndusInd Bank Ltd Revenue fell 5.1% to ₹53,480 crore, and its margin slipped from 19.9% to 18.2%. Retail is 63% of revenue. INDIE, IndusMobile, INDIE For Business, Indus Care, Indus Grande Care, PIONEER, PIONEER Private, PIONEER Private Banking Sells in 35 states and 3 countries; exports 0.0% of turnover |
₹53,480 Cr | -5.1% | — | — | 18.2% | 1.8% | — | 51.7 | 1.4% | +16.9% |
| IDFC First Bank Ltd Grew 11.5% to ₹47,733 crore but kept only 3.9% as profit, the lowest on the page, with a return on assets of 0.5%. |
₹47,733 Cr | +11.5% | — | — | 3.9% | 0.3% | 0.5% | 30.3 | 3.8% | +8.3% |
| Central Bank of India ₹41,991 crore, up 6.6%. Its margin improved from 13.2% to 15.3%, and treasury is 32% of revenue. |
₹41,991 Cr | +6.6% | — | — | 15.3% | 1.2% | 1.2% | 6.0 | 13.0% | -17.3% |
| Indian Overseas Bank ₹37,594 crore, up 13.9%, with a 26.9% margin and a 2.2% return on assets. Sells in 35 states and 4 countries; exports 0.0% of turnover |
₹37,594 Cr | +13.9% | — | — | 26.9% | 1.9% | 2.2% | 10.1 | 12.3% | -20.2% |
| Yes Bank Ltd ₹36,445 crore, up 2.4%. Its margin improved from 10.5% to 13.9% but is still below most peers. IRIS Biz, IRIS Biz by YES BANK, IRIS by YES BANK, YES Business Sells in 34 states and 89 countries; exports 0.64% of turnover |
₹36,445 Cr | +2.4% | — | — | 13.9% | 0.9% | 1.1% | 17.5 | 6.2% | -10.6% |
| IDBI Bank Ltd ₹35,302 crore, up 6.2%. Its 32.1% margin is the second highest on the page, and its return on assets is 2.4%. IDBI Advantage Savings Accounts, Utsav Fixed Deposits, IDBI Sameep Sells in 36 states and 1 countries; exports 0.0% of turnover |
₹35,302 Cr | +6.2% | — | — | 32.1% | 2.1% | 2.4% | 9.6 | 17.4% | -9.6% |
| Federal Bank Ltd ₹33,455 crore, up 5.6%, with a 16.2% margin. It reports two retail lines: other retail banking at 58% and digital banking at 6%. Sells in 31 states and 1 countries; exports 0.0% of turnover |
₹33,455 Cr | +5.6% | — | — | 16.2% | 1.0% | 1.4% | 17.3 | 11.4% | +52.9% |
| Bank of Maharashtra ₹32,618 crore, up 15.9%, the fastest growth among government-owned banks once the two bookkeeping cases are set aside. Its margin rose to 23.8%. |
₹32,618 Cr | +15.9% | — | — | 23.8% | 1.4% | 1.9% | 8.5 | 24.2% | +52.0% |
| UCO Bank ₹29,679 crore, almost flat (up 0.9%). Its margin improved to 14.5%. |
₹29,679 Cr | +0.9% | — | — | 14.5% | 0.8% | 1.1% | 10.5 | 9.5% | -23.4% |
| Bandhan Bank Ltd ₹23,949 crore, down 2.5%, with its margin down from 13.3% to 5.1%. Retail is 79% of revenue, the highest share on the page, and press reports link its weak year to stress in microfinance loans. |
₹23,949 Cr | -2.5% | — | — | 5.1% | 0.2% | 0.6% | 20.5 | 4.9% | +5.8% |
| AU Small Finance Bank Ltd The fastest-growing bank on the page, up 16.3% to ₹21,614 crore. It is a small finance bank, with 73% of revenue from other retail banking. AU0101 Sells in 25 states; exports 0.0% of turnover |
₹21,614 Cr | +16.3% | — | — | 16.1% | 0.6% | 1.9% | 25.9 | 14.2% | +28.3% |
| RBL Bank Ltd ₹18,464 crore, up 3.6%. Its margin is thin at 6.0%, though up from 3.5%. RBL MyBank, RBL Cares Chatbot Sells in 28 states and 1 countries; exports 0.0% of turnover |
₹18,464 Cr | +3.6% | — | — | 6.0% | 0.2% | 0.6% | 27.7 | 5.1% | +33.1% |
| Karur Vysya Bank Ltd The smallest bank on the page at ₹13,159 crore, but it has the highest margin, 33.6%, and grew 14.4%. KVB DLite Sells in 22 states; exports 0.0% of turnover |
₹13,159 Cr | +14.4% | — | — | 33.6% | 0.8% | — | 12.3 | 19.3% | +57.6% |
See every one of these companies in Valarth
Questions people ask
Who lends to India: the banks?
24 listed companies report their revenue from banking: State Bank of India (SBIN), HDFC Bank Ltd (HDFCBANK), ICICI Bank Ltd (ICICIBANK), Union Bank of India (UNIONBANK), Axis Bank Ltd (AXISBANK), Bank of Baroda (BANKBARODA), Canara Bank (CANBK), Punjab National Bank (PNB).
Which listed company earns the most from banking in India?
State Bank of India, with revenue from banking of ₹571,610 crore in FY26: 21.2% of the listed companies' total here.
How much do listed companies earn from banking?
The listed companies here earned ₹2,696,480 crore from banking in FY26, up 9.8% on FY25. Private makers are not included.
Which listed company makes the most profit from banking?
Karur Vysya Bank Ltd: its operating profit was 33.6% of its revenue from banking in FY26.
Are government banks or private banks bigger in India?
Among listed banks, the 11 directly government-owned banks earn 56.7% of banking revenue on the page's figures, led by SBI at 21.2%. RBI data show public sector banks took 50.8% of the deposits added in FY26. Private banks are now growing their deposits faster.
Why did bank profits come under pressure in FY26?
The RBI cut its repo rate by 1.25 percentage points in 2025. Loans linked to the repo rate got cheaper straight away, while deposit rates fell more slowly. Reported margins slipped at both private and state-owned banks in mid-2025. Some lenders, such as Bandhan, also had more unpaid small loans.
Which Indian bank is the most profitable for its size?
By margin, Karur Vysya (33.6%), IDBI Bank (32.1%), Kotak (28.5%) and ICICI Bank (27.5%) lead. By return on assets (profit as a share of everything the bank owns), ICICI Bank is highest at 2.7%, followed by IDBI at 2.4%, and HDFC Bank and Indian Overseas Bank at 2.2%.
What is the credit-deposit ratio and why does it matter?
It is the share of deposits that banks have lent out. The RBI puts it at about 82% in March 2026, up from 68.6% in September 2021. The higher it goes, the more banks depend on raising new deposits to keep lending.
Did Union Bank's revenue really grow 70%?
No. Its FY26 segment figures list retail and corporate banking twice. Counting them once gives an estimated ₹1,23,805 crore against ₹1,26,427 crore in FY25, a slight fall.
Who owns Mobile Omni Neo?
Mobile Omni Neo is a brand of Bank of India, listed on the NSE as BANKINDIA.
Who owns INDIE?
INDIE is a brand of IndusInd Bank Ltd, listed on the NSE as INDUSINDBK.
Who owns IndusMobile?
IndusMobile is a brand of IndusInd Bank Ltd, listed on the NSE as INDUSINDBK.
Who owns IRIS Biz?
IRIS Biz is a brand of Yes Bank Ltd, listed on the NSE as YESBANK.
Who owns IRIS Biz by YES BANK?
IRIS Biz by YES BANK is a brand of Yes Bank Ltd, listed on the NSE as YESBANK.