VALARTH See Mahindra & Mahindra Financial Services in the appOpen in app
M&MFIN · NSE · Non Banking Financial Company (NBFC)

Mahindra & Mahindra Financial Services Ltd

What the numbers mean, from its filings and the exchange. Data as of 12 Oct 2026.
Mid Cap · AMFI list Jan-Jun 2026 · Vendor sector: Financial Services
cheap low confidence No valuation within 120 days; P/E 13.7 vs peers 20.6 (4th of 14); P/B 1.6 vs peers 2.5 (4th of 14).
Statements through FY2026Prices adjusted for corporate actionsNot yet reviewed by the adversarial model

What is Mahindra & Mahindra Financial Services's share price today?

Mahindra & Mahindra Financial Services last traded at ₹322.40 on the NSE, as of 12 Oct 2026, 11:00 pm IST, up 0.9% on the day, up 12.4% over a year. Its 52-week range is ₹272 to ₹415. The live price is in the app.

₹322.40 +0.9% today
+12.4% over 1 year · NSE, as of 12 Oct 2026, 11:00 pm IST
60 month-end closes, 31 Oct 2021 to 30 Sep 2026, adjusted for splits and bonuses
52-week range35% of the way up
Low ₹272High ₹415

What is Mahindra & Mahindra Financial Services's market cap?

Mahindra & Mahindra Financial Services's market capitalisation is about ₹44,410 crore: what it would cost to buy every share at today's price. That makes it the 112th largest mid cap company we cover.

₹44,410 Cr Mid Cap112th largest mid cap company
Mid Cap means the companies ranked 101 to 250 by size, under SEBI's rules. Shares in issue are worked out from the market cap and the price. What market cap tells you →

Key facts

From the exchange
Symbol
NSE: M&MFIN
ISIN
INE774D01024
Cap bucket
Mid Cap, 112th largest by market cap
Industry (NSE)
Financial Services › Finance › Non Banking Financial Company (NBFC)
Listed since
2006
Futures and options
Not traded

Is Mahindra & Mahindra Financial Services overvalued?

Cheap, with low confidence: no valuation within 120 days; P/E 13.7 vs peers 20.6 (4th of 14); P/B 1.6 vs peers 2.5 (4th of 14).

Valuation

Latest price and trailing 12 months
P/E 13.65
vs peers 20.6 · 4th of 14
Price divided by last year's earnings per share: how many years of today's profit you pay for. Learn more →
P/B 1.61
vs peers 2.5 · 4th of 14
Price divided by book value per share: what you pay for each rupee of net assets on the balance sheet. Learn more →
Market cap ₹44,410 Cr
Total market value of all shares, in ₹ crore. Learn more →
Dividend yield 2.6%
vs peers 0.8% · 1st of 8
Last year's dividends as a share of today's price. Learn more →
PEG (vendor) 2.47
vs peers 2.8 · 6th of 13
P/E divided by the vendor's earnings growth figure, which it does not disclose; a P/E adjusted for how fast profits grow. Learn more →
PEG on our 3-year EPS growth 1.44
P/E divided by the 3-year EPS growth rate from the stored accounts. Learn more →
3 models could be judged
Skipped — Fair value, EPV, Graham number, Graham value, Lynch, Owner earnings: no valuation stored

Our valuation range

🔒 Pro
Value range, implied growth at today's price, and the nine models behind it: in the app.

Is Mahindra & Mahindra Financial Services a quality business?

Quality score 28.2, 13th of 14 in its peer set; WATCH on 15 of 22 lender flags judged.

Quality and risk

Data as of 12 Oct 2026
Business quality Not available
The kind of business, which sets the yardstick it is judged by. Learn more →
Quality score 28.2
vs peers 43.8 · 13th of 14
Returns, margins, leverage and consistency against its peers, out of 100. Learn more →
Risk level WATCH
15 of 22 lender flags judged
From flags on debt, earnings quality, dilution and price swings. Learn more →

Lender scorecard

Statements through FY2026 (Mar-26)
Basis: consolidated accounts, FY2026 (Mar-26) against FY2025; NSE/BSE XBRL, the Q4 results filing; NIM is interest earned less expended over average advances and investments; cost to income is operating expenses over net interest income plus other income; credit cost is FY2026 provisions over average advances (the loan book from the Q4 filing); ROA over average total assets; ROE over average equity
Net interest margin 6.8%
vs peers 8.4% · 11th of 14
What a lender earns on its loans and investments less what it pays for deposits and borrowings, as a share of the assets that earn interest (or of all assets where the split is not filed). Learn more →
Gross NPA Not available
Loans on which repayment has stopped, as a share of all loans, before any provision against them; from the latest results filing. Learn more →
Net NPA Not available
Bad loans after the provisions already set aside against them, as a share of loans. Learn more →
Provision coverage Not available
How much of the gross bad loans has already been provided for. Learn more →
Credit cost 1.9%
vs peers 1.8% · 8th of 13
The year's provisions for bad loans as a share of the average loan book. Learn more →
Cost to income 60.4%
vs peers 53.1% · 11th of 14
Operating expenses (staff, branches, technology) over net interest income plus other income. Learn more →
Return on assets 1.9%
vs peers 2.3% · 10th of 14
Profit as a share of average total assets. Learn more →
CET1 ratio Not available
Common equity tier 1 capital, the hardest kind, against risk-weighted assets; from the latest results filing. Learn more →
Loan growth YoY 12.8%
vs peers 28.1% · 8th of 10
Growth in the loan book over the latest fiscal year. Learn more →
Deposit growth YoY 24.2%
Growth in deposits over the latest fiscal year. Learn more →
CASA ratio Not available
Current and savings account balances as a share of all deposits. Learn more →
Inside the app

Get a sneak peek of Valarth

Start freeStart free
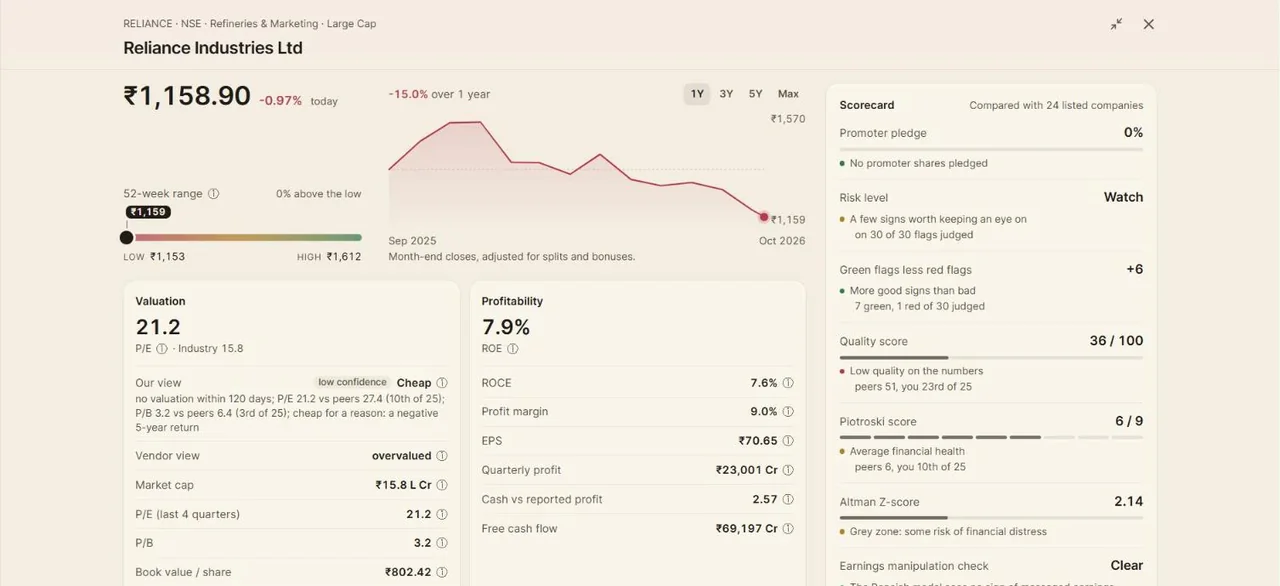
A Valarth stock page: the share price with its chart and 52-week range, valuation and profitability figures, and a scorecard of health checks.
Stock pagePrice, valuation, profitability and a scorecard of health checks for every company, each figure explained.
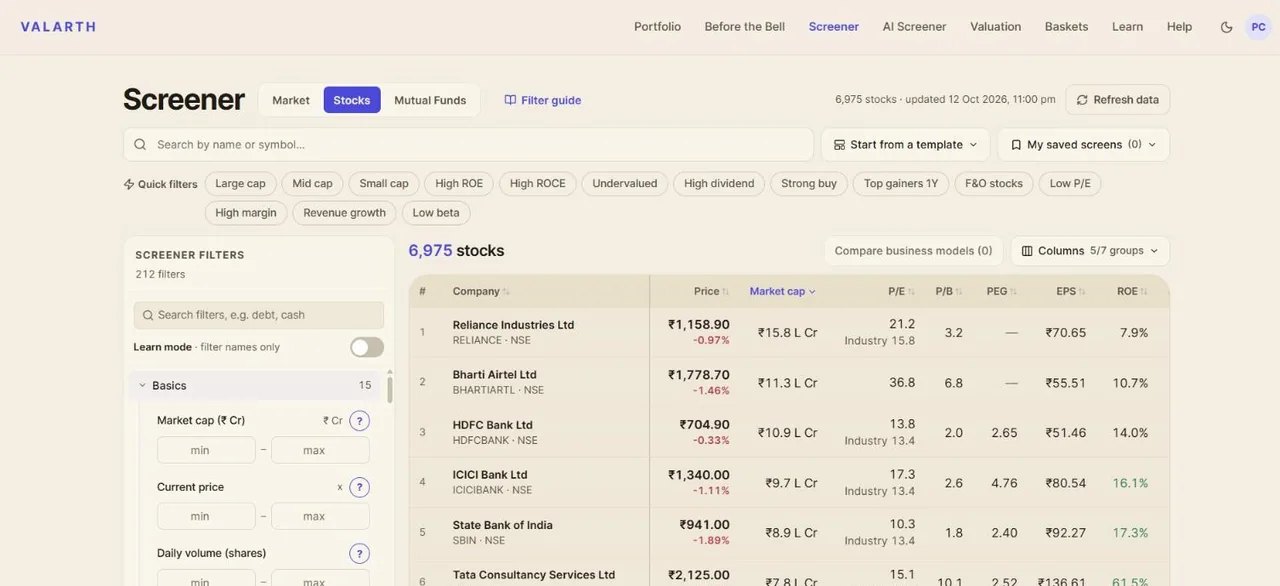
The Valarth stock screener: a table of companies with price, market cap, P/E, P/B, PEG, EPS and ROE, and filters down the left.
ScreenerEvery listed company, filtered on 212 figures, each with a plain-language lesson beside it.
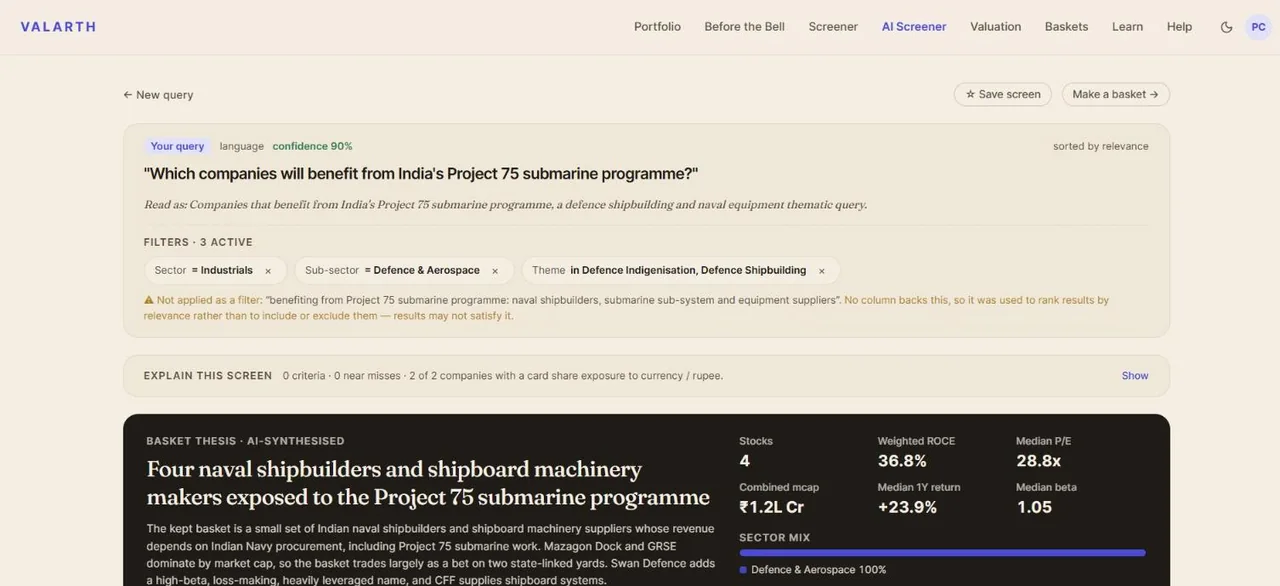
The Valarth AI Screener answering 'Which companies will benefit from India's Project 75 submarine programme?' with a basket of four naval shipbuilders and a written thesis.
AI ScreenerAsk a question in plain English, like which companies benefit from India's Project 75. It reads the intent, builds the screen and writes the thesis.
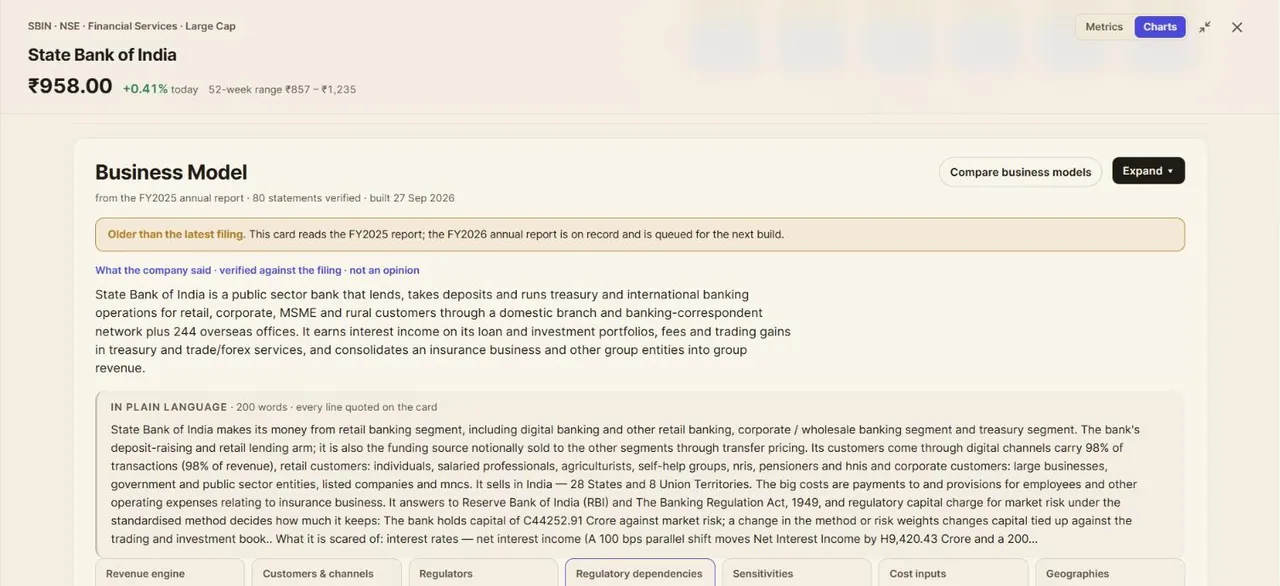
A Valarth business-model card for State Bank of India, with a plain-language summary and statements verified against the filing.
Business modelHow a company makes money and what can hurt it, each statement checked against its annual report.
Valarth's Before the Bell edition, with the day's headline, regulator notes and sector moves.
Before the BellA morning edition before the market opens: what moved, which rule changed, and what it means for your holdings.

Has Mahindra & Mahindra Financial Services made money for shareholders?

Yes: +12.4% over one year and +11.9% a year over five years.

Shareholder returns

1-year return +12.4%
Price only
What the share price did over the last 12 months. Learn more →
5-year return +11.9% a year
Price only
Yearly average price return over five years, bonuses and splits adjusted. Learn more →
Wealth destroyer No
Five-year total return — price CAGR on bonus- and split-adjusted closes plus the dividend yield — below the 7% a bank fixed deposit paid. Learn more →

Returns

3Y and 5Y are yearly averages
1W
−2.1%
1M
−6.7%
3M
−4.0%
6M
+7.6%
1Y
+12.4%
3Y
+9.8%
5Y
+11.9%

Does Mahindra & Mahindra Financial Services pay a dividend?

Yes. Mahindra & Mahindra Financial Services's dividend yield is 2.62% at the latest price; the last payout was ₹7.50 a share, ex-dividend 13 Jul 2026.

Dividends

Per share, by ex-dividend date
Dividend yield2.62%
The past 12 months' dividends as a share of today's price.
13 Jul 2026 · Final₹7.50
15 Jul 2025 · Final₹6.50
16 Jul 2024 · Final₹6.13
21 Jul 2023 · Final₹5.84
20 Jul 2022 · Final₹3.50
Payout ratio🔒 In the app
The share of profit paid out as dividends; a very high share leaves little to reinvest.
Dividend growth, 5 years🔒 In the app
How fast the dividend per share has grown a year.
Years without a miss🔒 In the app
How many years in a row a dividend has been paid.

Is Mahindra & Mahindra Financial Services growing?

Loan growth 12.8%; deposit growth 24.2%; revenue 3 years 18.0% a year.

Growth

Statements through FY2026 (Mar-26)
Loan growth 12.8%
vs peers 28.1% · 8th of 10
Growth in the loan book over the latest fiscal year. Learn more →
Deposit growth 24.2%
Growth in deposits over the latest fiscal year. Learn more →
Revenue 3 years 18.0% a year
vs peers 26.3% · 9th of 14
Compound annual growth of revenue over three years. Learn more →
EPS 3 years 9.5% a year
Growth in earnings per share, so dilution counts against the company. Learn more →
Revenue 5 years 13.8% a year
Compound annual growth of revenue over five years. Learn more →
EPS 5 years 26.2% a year
Growth in earnings per share over five years, so dilution counts against the company. Learn more →

How did Mahindra & Mahindra Financial Services do last quarter?

Mahindra & Mahindra Financial Services reported income of ₹5,747 Cr, up 13.6% on a year earlier and a net profit of ₹927 Cr, up 26.6% in the Jun 2026 quarter.

Latest quarter

Jun 2026
Income, latest quarter₹5,747 Cr
+13.6% on a year earlier
What the company took in over the quarter.
Net profit, latest quarter₹927 Cr
+26.6% on a year earlier
What was left for shareholders after every cost and tax.

How does Mahindra & Mahindra Financial Services compare with its peers?

Compared with 13 Non Banking Financial Company (NBFC); 4th of 14 on P/E; 13th of 14 on quality score.

Compared with 13 Non Banking Financial Company (NBFC)

13 companies

Mahindra & Mahindra Financial Services against its peers

Largest 10 of 13 peers, by market cap
CompanyMarket capP/EP/BROE1YQuality 🔒Rank 🔒
Mahindra & Mahindra Financial Services Ltd₹44,410 Cr13.71.612.5%+12.4%
Tata Capital Ltd₹1.4 L Cr24.73.49.6%−3.6%
Muthoot Finance Ltd₹1.1 L Cr9.33.430.6%−18.3%
SBI Cards & Payment Services Ltd₹53,482 Cr23.53.814.7%−39.0%
HDB Financial Services Ltd₹48,905 Cr17.72.213.9%−20.4%
Authum Investment & Infrastructure Ltd₹46,682 Cr22.22.513.2%−13.6%
Piramal Finance Ltd₹46,645 Cr26.41.55.5%+49.0%
Sundaram Finance Ltd₹45,704 Cr20.43.815.4%−7.1%
Poonawalla Fincorp Ltd₹39,389 Cr34.92.95.9%−15.3%
Manappuram Finance Ltd₹29,570 Cr19.21.511.0%+9.9%
Peer median—20.62.514.7%−4.2%
Market cap in rupees crore; P/E and P/B on the latest price; 1Y is the price return over a year. A dash is a figure that does not apply or is not reported.

Full peer comparison

🔒 Pro
Every peer, every figure, the ranks and the quality and forensic scores side by side: in the app.

Who owns Mahindra & Mahindra Financial Services?

Mahindra & Mahindra Financial Services is held by promoters 52.5%, foreign institutions 9.5%, domestic institutions 31.5%.

Shareholding pattern

Latest filing, percent of shares
Promoters52.5%
The founders and controlling group.
Foreign institutions9.5%
Overseas funds investing through the FPI route.
Domestic institutions31.5%
Indian insurers, banks, pension and mutual funds together.
Mutual funds16.7%
Indian mutual fund schemes; part of domestic institutions.
Retail and others3.9%
Individual investors and everyone else.
Promoter shares pledged🔒 In the app
Promoter shares given as collateral for loans; a high share is a risk to watch.
Holding trend🔒 In the app
Whether promoters, foreign funds and mutual funds have been adding or selling over recent quarters.

What do analysts say about Mahindra & Mahindra Financial Services?

33 analysts cover Mahindra & Mahindra Financial Services, and the consensus is buy. A consensus is a count of opinions, not a forecast; read it beside the numbers.

Analyst consensus

33 analysts
ConsensusBuy
The rating most covering analysts give the share.
Average target price🔒 In the app
The mean of the analysts' 12-month price targets.
Upside to target🔒 In the app
How far the target sits above or below today's price.
Share rating it a buy🔒 In the app
The share of covering analysts with a buy rating.

What does Mahindra & Mahindra Financial Services do and what is it sensitive to?

Mahindra Finance is a non-banking financial company that finances vehicles, tractors, commercial vehicles, SMEs and housing, and distributes insurance, mainly for customers in rural and semi-urban India (chunks 39, 55). Sensitive to: interest rates and borrowing costs.

Business-model card

FY2025 · 44 verified
5Revenue
5Channels
2Regulators
5Reg. dependencies
6Sensitivities
4Costs
2Geographies

Mahindra Finance is a non-banking financial company that finances vehicles, tractors, commercial vehicles, SMEs and housing, and distributes insurance, mainly for customers in rural and semi-urban India (chunks 39, 55). Interpretation: it earns mainly interest on loans and leases, plus fee, commission and distribution income (chunks 48, 50).

Revenue by segment

year ended March 31, 2025 (consolidated; Ind AS 108 table, External Revenue row)
Financing Activities92.2%
Others7.8%

Revenue engine

5 verified
Financing and leasing of automobiles, tractors, commercial vehicles, SMEs and housing
Segment 'Financing activities' is the core lending line. Interpretation: it earns interest on loans and lease income, recognised over time using the effective interest method.
Vehicle finance portfolio
The vehicle finance book grew 16% year on year, so it remains the main driver of loan income.
Non-vehicle finance (SME, leasing, insurance, mortgages)
The company says this portfolio grew 30% and is meant to reduce dependence on vehicle finance.
2 more statements
Insurance broking and distribution
Earns distribution and commission income by selling life, health, motor and property policies from partner insurers. Interpretation: the excerpt does not say how the gross premium KPIs split between products.
Insurance broking, asset management and trusteeship (other segment)
Listed as a separate activity category in the segment note. Interpretation: revenue is not separately quantified in the excerpt.

Customers & channels

5 verified
Rural and semi-urban retail and small-business borrowers
Core customer base. Interpretation: the excerpt ties their repayment ability to rural income drivers.
Agriculture, transport and SME customers buying vehicles, tractors and equipment
Customers borrow to buy income-generating assets, so their demand follows the sectors they serve.
Dealers and OEMs
Dealer relationships are managed through key account management for high-potential dealers. Interpretation: dealers act as the origination channel for vehicle loans.
2 more statements
Bank co-lending partners (SBI, BoB)
Co-lends and co-originates prime-segment loans with major banks, which adds a partner-funded origination channel.
Branch and field network
Physical network used for sales, collections and cross-sell of insurance.

Regulators

2 verified
Reserve Bank of India (RBI)
Governs the company's NBFC licence, its Upper Layer scale-based classification, capital adequacy, asset classification and liquidity.
RBI inspection under Section 45N of the RBI Act, 1934
RBI inspection reports are noted by the Board, so supervisory findings feed into governance.

Regulatory dependencies

5 verified
Scale Based Regulation Directions, 2023 (Upper Layer NBFC)
Requires mandated policies such as Large Exposure and ICAAP. Interpretation: a change in these requirements would raise compliance cost and affect how much capital the company must hold.
Liquidity coverage ratio minimum
The company reports an LCR above the mandatory minimum. Interpretation: a higher minimum or a change in liquid-asset rules would tighten funding and liquidity buffers.
Capital adequacy and asset classification norms
Compliance with these norms governs how much capital the company must hold against its loan book.
2 more statements
Government auto and EV schemes (Auto PLI, PM E-Drive, ACC PLI, PM e-Bus Sewa)
Scheme allocations are expected to raise vehicle demand. Interpretation: scheme funding or eligibility changes would move the vehicle financing volume.
New personal income tax regime
Income exemption raises disposable income. Interpretation: tax changes affect borrowers' ability to buy vehicles.

Sensitivities

6 verified
Interest rates and borrowing costs
Direction: rising borrowing costs squeeze margins for NBFCs, and funding constraints hit smaller players hardest. Interpretation: a rate cut lowers funding cost and, per the excerpt, lifts vehicle demand.
RBI rate cuts and tax reform
Direction: rate cuts are expected to increase demand, especially in rural and semi-urban areas, and to improve access to vehicle financing.
Monsoon and agricultural income
Direction: poor agricultural output or adverse climate lowers customer income, which the company says can impair loan assets.
3 more statements
Credit risk on unbanked rural base and collateral values
Direction: higher delinquency or lower collateral value increases credit losses. Interpretation: collateral values fall in a downturn, which raises loss given default.
Investment pricing risk
Direction: a 5 percent rise in market price adds to profit before tax on the investment book. Interpretation: a fall would have the reverse effect.
Extreme weather events
Direction: floods, wildfires and heatwaves cause human and economic losses, which the company lists as an emerging risk relevant to its operations.

Cost inputs

4 verified
Finance costs (borrowings)
Interest paid on bank loans, NCDs, deposits, CPs and securitisation liabilities. Finance costs were 7,898.30 in FY2025 against 6,426.94 in FY2024.
Funding from lenders
A positive lender relationship allows growth capital to be raised in a timely and cost-effective manner. Interpretation: the funding cost depends on lender terms.
Employee benefits expenses
Staff cost line, 1,903.13 in FY2025 against 1,712.63 in FY2024.
1 more statement
Cloud and technology infrastructure
Multi-cloud architecture is said to produce cost efficiencies and optimised resource use. Interpretation: this is an ongoing technology cost line.

Geographies

2 verified
India (domestic operations)
Business is concentrated in India, with 27 states and 7 union territories served. Interpretation: the company reports only a domestic segment.
Joint venture Mahindra Finance USA LLC (United States)
Joint venture, not part of the BRSR boundary. Interpretation: its numbers are not included in the company's own figures.
Each statement is checked word for word against the FY2025 annual report; the passages are in the app.

What changed recently?

Q1 FY2027 results filed (21 Jul 2026).

Change log

6 entries · newest first
  1. Results filedQ1 FY2027 results filed.
  2. Results filedQ4 FY2026 results filed.
  3. Results filedQ3 FY2026 results filed.
  4. Results filedQ2 FY2026 results filed.
  5. Results filedQ1 FY2026 results filed.
  6. Results filedQ4 FY2025 results filed.
Get alerts →Sign in to be told when any of these change.

What this page does not tell you

What could not be judged, and why. Never empty.
  • Models not runFair value, EPV, Graham number, Graham value, Lynch, Owner earnings: no valuation stored.
  • FlagsWATCH on 15 of 22 lender flags judged; 1 red; 7 could not be judged.
  • ForensicsForensic scores withheld: rights issue 2025-05-14.
  • Data gapsBusiness quality, Gross NPA, Net NPA, Provision coverage, CET1 ratio, CASA ratio: not available yet.
Not applicable to a bank, lender or insurer · 12
  • Altman ZAltman Z reads working capital and sales over assets, which a lender's balance sheet does not have.
  • Piotroski F-scorePiotroski's leverage and liquidity checks read deposits and borrowings as weakness.
  • Beneish M-scoreThe Beneish model reads receivables, margins and depreciation that a lender's accounts do not report.
  • Operating marginInterest is a lender's cost of goods, so operating profit before interest is not defined.
  • Interest coverageInterest is a lender's main cost, not a charge on operating profit.
  • Debt to equityBorrowings and deposits are a lender's raw material; gearing is judged by capital adequacy instead.
  • EV/EBITDAEnterprise value adds borrowings to market cap; for a lender borrowings are the business, not a claim on it.
  • FCF yieldOperating cash flow less capex is not free cash flow for a lender: loan growth sits in operating cash flow.
  • Cash conversion cycleA lender's receivables are its loan book, not invoices waiting to be paid.
  • Asset turnoverA lender earns a spread on its assets, not a turnover of them.
  • ROCEEBIT over capital employed reads a lender's interest income against its borrowings; return on assets and return on equity are the lender's measures.
  • ROCE, 10-year averageEBIT over capital employed reads a lender's interest income against its borrowings; return on assets is the lender's measure (HDFC Bank's 1.7% ten-year ROCE means nothing).

What this page rests on

✓10 years of annual statements, through FY2026 (Mar-26)✓10 quarters of results✓247 months of month-end prices, adjusted for bonuses and splits○no valuation of ours yet✓business-model card FY2025 · 44 verified

Questions people ask

What is Mahindra & Mahindra Financial Services's share price today?

Mahindra & Mahindra Financial Services last traded at ₹322.40 on the NSE, as of 12 Oct 2026, 11:00 pm IST, up 0.9% on the day, up 12.4% over a year. Its 52-week range is ₹272 to ₹415. The live price is in the app.

What is Mahindra & Mahindra Financial Services's market cap?

Mahindra & Mahindra Financial Services's market capitalisation is about ₹44,410 crore: what it would cost to buy every share at today's price. That makes it the 112th largest mid cap company we cover.

Is Mahindra & Mahindra Financial Services Ltd a large cap, mid cap or small cap?

Mahindra & Mahindra Financial Services Ltd (M&MFIN) is a mid cap company in AMFI's classification for Jan-Jun 2026. SEBI's buckets go by rank on six-month average market capitalisation: the top 100 are large caps, 101 to 250 mid caps, the rest small caps.

What is Mahindra & Mahindra Financial Services Ltd's P/E ratio?

13.65, vs peers 20.6 · 4th of 14. Price divided by last year's earnings per share: how many years of today's profit you pay for.

Is Mahindra & Mahindra Financial Services Ltd overvalued?

Cheap, with low confidence: no valuation within 120 days; P/E 13.7 vs peers 20.6 (4th of 14); P/B 1.6 vs peers 2.5 (4th of 14).

How does Mahindra & Mahindra Financial Services Ltd make money?

Mahindra Finance is a non-banking financial company that finances vehicles, tractors, commercial vehicles, SMEs and housing, and distributes insurance, mainly for customers in rural and semi-urban India (chunks 39, 55). Interpretation: it earns mainly interest on loans and leases, plus fee, commission and distribution income (chunks 48, 50).

Why is there no Altman Z or debt to equity for Mahindra & Mahindra Financial Services?

Borrowing is a bank's or lender's raw material, so those ratios mislead. Net interest margin, gross NPA, return on assets and the capital ratios are shown instead.

Who are Mahindra & Mahindra Financial Services Ltd's peers?

Compared with 13 Non Banking Financial Company (NBFC): Cholamandalam Investment & Finance Company Ltd, Tata Capital Ltd, Muthoot Finance Ltd, SBI Cards & Payment Services Ltd, HDB Financial Services Ltd and 8 more. The app shows how they compare on every figure.

Is this investment advice?

No. Valarth is a research and learning tool and is not a SEBI-registered investment adviser or research analyst. The figures come from the company's filings and the exchanges; what to do with them is your call.

How did Mahindra & Mahindra Financial Services do last quarter?

Mahindra & Mahindra Financial Services reported income of ₹5,747 Cr, up 13.6% on a year earlier and a net profit of ₹927 Cr, up 26.6% in the Jun 2026 quarter.

Who owns Mahindra & Mahindra Financial Services?

Mahindra & Mahindra Financial Services is held by promoters 52.5%, foreign institutions 9.5%, domestic institutions 31.5%.

Does Mahindra & Mahindra Financial Services pay a dividend?

Yes. Mahindra & Mahindra Financial Services's dividend yield is 2.62% at the latest price; the last payout was ₹7.50 a share, ex-dividend 13 Jul 2026.

What do analysts say about Mahindra & Mahindra Financial Services?

33 analysts cover Mahindra & Mahindra Financial Services, and the consensus is buy. A consensus is a count of opinions, not a forecast; read it beside the numbers.

Everything on Mahindra & Mahindra Financial Services, and 6,621 other companies, with 212 filters and the full peer tables