VALARTH See Avenue Supermarts in the appOpen in app
DMART · NSE · Diversified Retail

Avenue Supermarts Ltd

What the numbers mean, from its filings and the exchange. Data as of 12 Oct 2026.
Large Cap · AMFI list Jan-Jun 2026 · Vendor sector: Consumer Defensive
fair low confidence No valuation within 120 days; P/E 73.5 vs peers 131 (3rd of 7); P/B 10.1 vs peers 6.6 (8th of 10).
Statements through FY2026Prices adjusted for corporate actionsNot yet reviewed by the adversarial model

What is Avenue Supermarts's share price today?

Avenue Supermarts last traded at ₹3,364.90 on the NSE, as of 12 Oct 2026, 11:00 pm IST, down 4.3% on the day, down 16.3% over a year. Its 52-week range is ₹3,351 to ₹4,644. The live price is in the app.

₹3,364.90 −4.3% today
−16.3% over 1 year · NSE, as of 12 Oct 2026, 11:00 pm IST
60 month-end closes, 31 Oct 2021 to 30 Sep 2026, adjusted for splits and bonuses
52-week range1% of the way up
Low ₹3,351High ₹4,644

What is Avenue Supermarts's market cap?

Avenue Supermarts's market capitalisation is about ₹2.29 lakh crore: what it would cost to buy every share at today's price. That makes it the 38th largest large cap company we cover.

₹2.3 L Cr Large Cap38th largest large cap company
Large Cap means the 100 largest listed companies, under SEBI's rules. Shares in issue are worked out from the market cap and the price. What market cap tells you →

Key facts

From the exchange
Symbol
NSE: DMART
ISIN
INE192R01011
Cap bucket
Large Cap, 38th largest by market cap
Industry (NSE)
Consumer Discretionary › Consumer Services › Retailing › Diversified Retail
Listed since
2017
Futures and options
Traded

Is Avenue Supermarts overvalued?

Fair, with low confidence: no valuation within 120 days; P/E 73.5 vs peers 131 (3rd of 7); P/B 10.1 vs peers 6.6 (8th of 10).

Valuation

Latest price and trailing 12 months
P/E 73.51
vs peers 131.5 · 3rd of 7
Price divided by last year's earnings per share: how many years of today's profit you pay for. Learn more →
P/B 10.12
vs peers 6.6 · 8th of 10
Price divided by book value per share: what you pay for each rupee of net assets on the balance sheet. Learn more →
Market cap ₹2.29 lakh Cr
Total market value of all shares, in ₹ crore. Learn more →
Dividend yield Not available
Last year's dividends as a share of today's price. Learn more →
PEG (vendor) 12.59
vs peers 12.1 · 3rd of 5
P/E divided by the vendor's earnings growth figure, which it does not disclose; a P/E adjusted for how fast profits grow. Learn more →
PEG on our 3-year EPS growth 9.79
P/E divided by the 3-year EPS growth rate from the stored accounts. Learn more →
3 models could be judged
Skipped — Fair value, EPV, Graham number, Graham value, Lynch, Owner earnings: no valuation stored

Our valuation range

🔒 Pro
Value range, implied growth at today's price, and the nine models behind it: in the app.

Is Avenue Supermarts a quality business?

Quality score 59.3, 2nd of 10 in its peer set; WATCH on 30 of 30 flags judged.

Quality and risk

Data as of 12 Oct 2026
Business quality Not available
The kind of business, which sets the yardstick it is judged by. Learn more →
Quality score 59.3
vs peers 41.5 · 2nd of 10
Returns, margins, leverage and consistency against its peers, out of 100. Learn more →
Risk level WATCH
30 of 30 flags judged
From flags on debt, earnings quality, dilution and price swings. Learn more →

Profitability

ROE 13.5%
vs peers 5.9% · 2nd of 8
Return on equity: profit as a share of shareholders' money. Learn more →
ROCE 17.5%
vs peers 7.6% · 2nd of 8
Return on capital employed: operating profit as a share of all the capital in the business, debt and equity. Learn more →
Profit margin 4.3%
vs peers 2.4% · 5th of 10
Profit after everything, as a share of revenue. Learn more →
EPS ₹45.55
Trailing 12 months
Profit for each share over the last 12 months.

Scorecard

🔒 Pro
Health scores and red flags with their values and history: in the app.
Inside the app

Get a sneak peek of Valarth

Start freeStart free
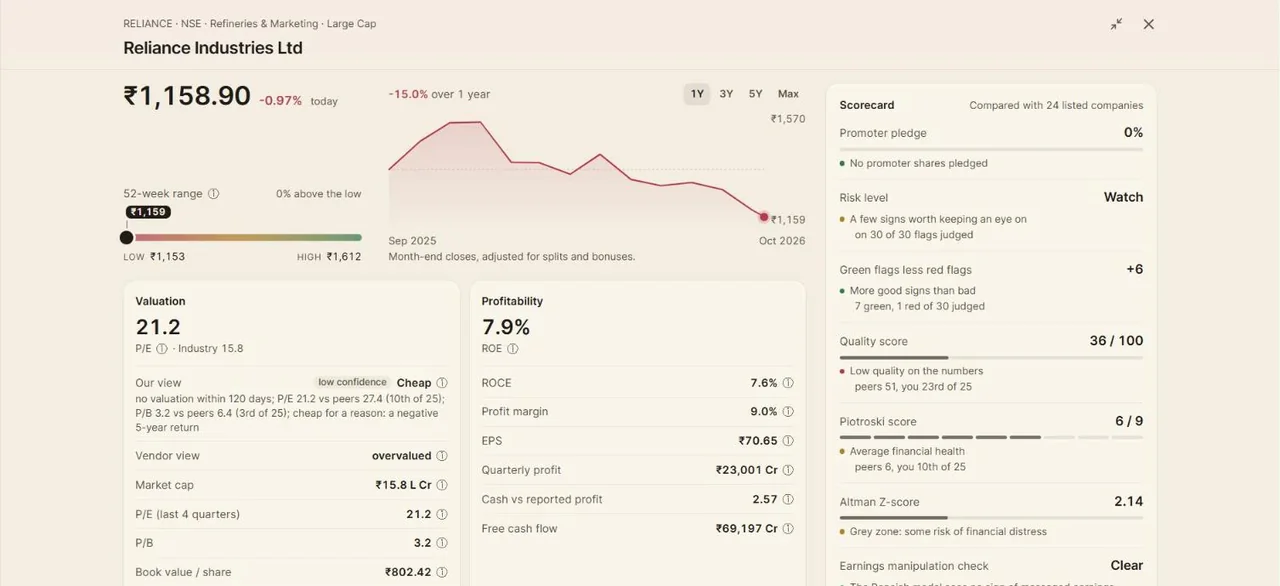
A Valarth stock page: the share price with its chart and 52-week range, valuation and profitability figures, and a scorecard of health checks.
Stock pagePrice, valuation, profitability and a scorecard of health checks for every company, each figure explained.
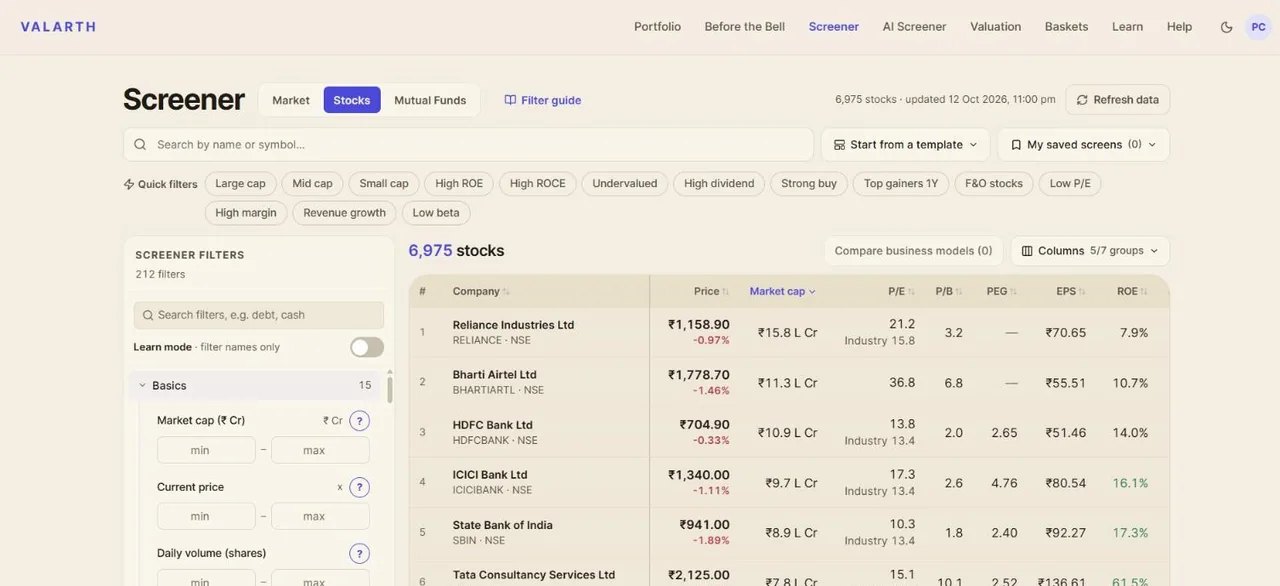
The Valarth stock screener: a table of companies with price, market cap, P/E, P/B, PEG, EPS and ROE, and filters down the left.
ScreenerEvery listed company, filtered on 212 figures, each with a plain-language lesson beside it.
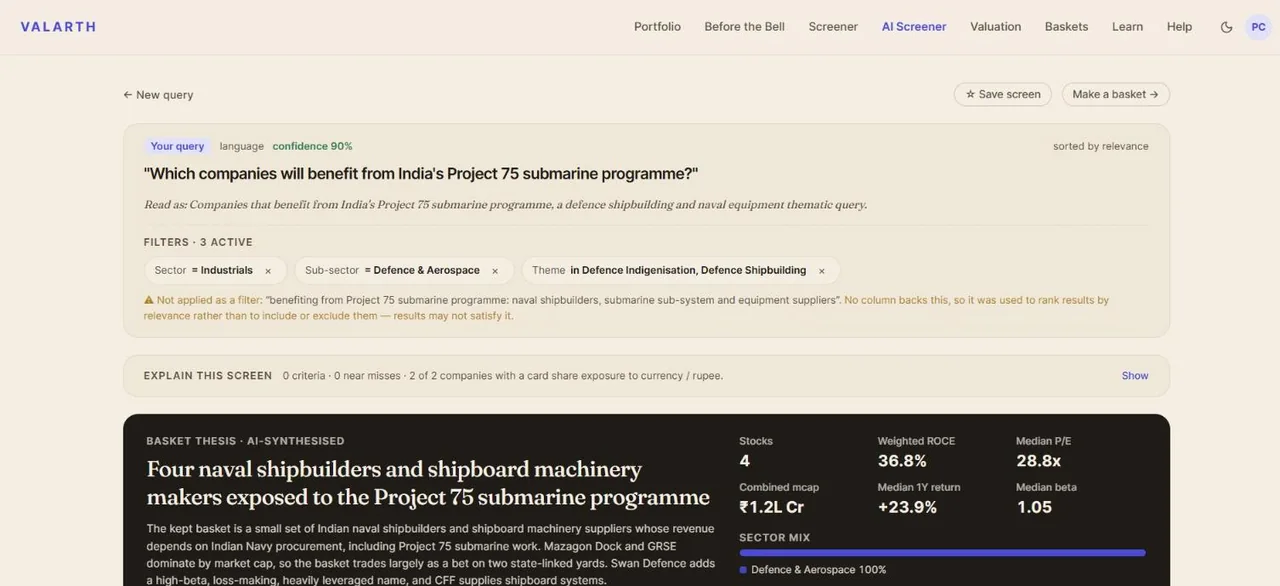
The Valarth AI Screener answering 'Which companies will benefit from India's Project 75 submarine programme?' with a basket of four naval shipbuilders and a written thesis.
AI ScreenerAsk a question in plain English, like which companies benefit from India's Project 75. It reads the intent, builds the screen and writes the thesis.
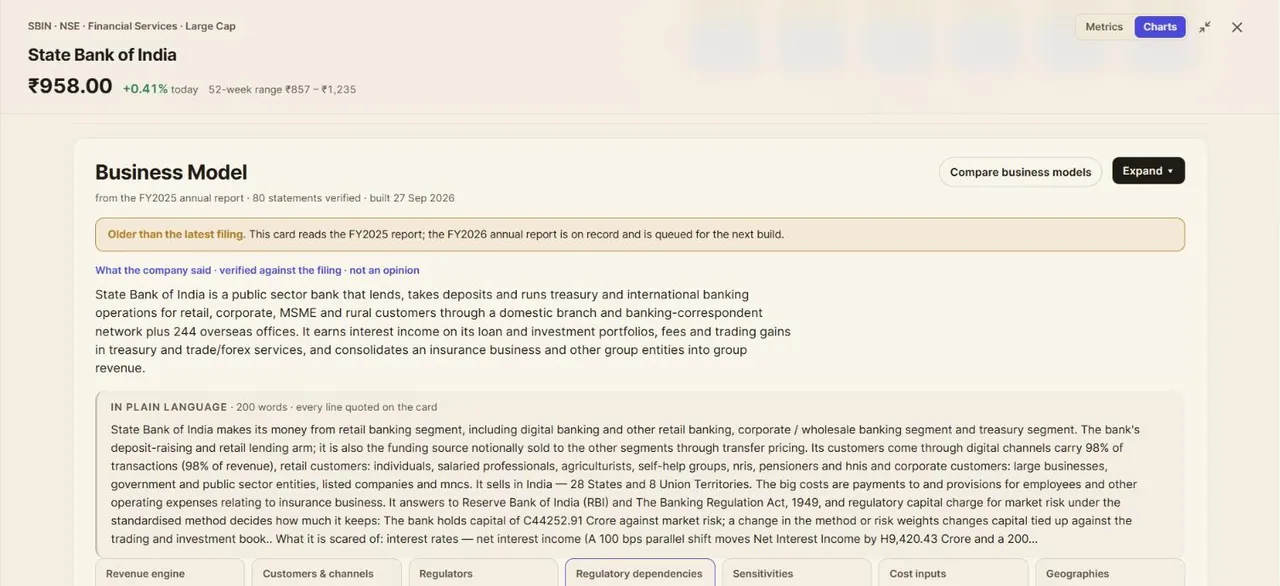
A Valarth business-model card for State Bank of India, with a plain-language summary and statements verified against the filing.
Business modelHow a company makes money and what can hurt it, each statement checked against its annual report.
Valarth's Before the Bell edition, with the day's headline, regulator notes and sector moves.
Before the BellA morning edition before the market opens: what moved, which rule changed, and what it means for your holdings.

Has Avenue Supermarts made money for shareholders?

Not over these periods: −16.3% over one year and −2.2% a year over five years.

Shareholder returns

1-year return −16.3%
Price only
What the share price did over the last 12 months. Learn more →
5-year return −2.2% a year
Price only
Yearly average price return over five years, bonuses and splits adjusted. Learn more →
Wealth destroyer Yes
Five-year total return — price CAGR on bonus- and split-adjusted closes plus the dividend yield — below the 7% a bank fixed deposit paid. Learn more →

Returns

3Y and 5Y are yearly averages
1W
−1.4%
1M
−4.4%
3M
−11.9%
6M
−20.9%
1Y
−16.3%
3Y
+1.5%
5Y
−2.2%

Is Avenue Supermarts growing?

Revenue 3 years 17.0% a year; profit 3 years 7.7% a year; revenue 5 years 18.1% a year.

Growth

Statements through FY2026 (Mar-26)
Revenue 3 years 17.0% a year
vs peers 31.8% · 10th of 10
Compound annual growth of revenue over three years. Learn more →
Profit 3 years 7.7% a year
Compound annual growth of net profit over three years. Learn more →
Revenue 5 years 18.1% a year
Compound annual growth of revenue over five years. Learn more →
Profit 5 years 15.4% a year
Compound annual growth of net profit over five years. Learn more →
EPS 3 years 7.5% a year
Growth in earnings per share, so dilution counts against the company. Learn more →
EPS 5 years 21.9% a year
Growth in earnings per share over five years, so dilution counts against the company. Learn more →
P/E vs own history -30.1%
Today's P/E against its own 5-year median; negative is cheaper than its history. Learn more →

How did Avenue Supermarts do last quarter?

Avenue Supermarts reported revenue of ₹19,644 Cr, up 15.9% on a year earlier and a net profit of ₹743 Cr, up 9.7% in the Jun 2026 quarter.

Latest quarter

Jun 2026
Revenue, latest quarter₹19,644 Cr
+15.9% on a year earlier
What the company took in over the quarter.
Net profit, latest quarter₹743 Cr
+9.7% on a year earlier
What was left for shareholders after every cost and tax.

How does Avenue Supermarts compare with its peers?

Compared with 9 Retailing (the industry, as the basic industry was too small); 3rd of 7 on P/E; 2nd of 10 on quality score.

Compared with 9 Retailing (the industry, as the basic industry was too small)

9 companies

Avenue Supermarts against its peers

Largest 9 of 9 peers, by market cap
CompanyMarket capP/EP/BROEROCE1YQuality 🔒Rank 🔒
Avenue Supermarts Ltd₹2.3 L Cr73.510.113.5%17.5%−16.3%
Eternal Ltd₹3.1 L Cr688.25.77.3%8.2%−7.2%
Trent Ltd₹1.6 L Cr86.015.228.9%29.2%−6.5%
Lenskart Solutions Ltd₹1.2 L Cr176.99.55.9%7.6%+68.1%
Meesho Ltd₹1.1 L Cr—1.94.5%5.8%+36.8%
FSN E-Commerce Ventures Ltd₹98,245 Cr385.437.35.1%6.6%+31.2%
Info Edge (India) Ltd₹79,042 Cr49.41.8-1.6%4.8%−8.6%
Swiggy Ltd₹64,647 Cr—3.2——−46.1%
Vishal Mega Mart Ltd₹45,677 Cr51.07.09.9%13.2%−34.0%
Urban Company Ltd₹24,638 Cr—6.6——+2.6%
Peer median—131.56.65.9%7.6%−6.5%
Market cap in rupees crore; P/E and P/B on the latest price; 1Y is the price return over a year. A dash is a figure that does not apply or is not reported.

Full peer comparison

🔒 Pro
Every peer, every figure, the ranks and the quality and forensic scores side by side: in the app.

Who owns Avenue Supermarts?

Avenue Supermarts is held by promoters 74.5%, foreign institutions 9.2%, domestic institutions 8.7%.

Shareholding pattern

Latest filing, percent of shares
Promoters74.5%
The founders and controlling group.
Foreign institutions9.2%
Overseas funds investing through the FPI route.
Domestic institutions8.7%
Indian insurers, banks, pension and mutual funds together.
Mutual funds6.6%
Indian mutual fund schemes; part of domestic institutions.
Retail and others2.7%
Individual investors and everyone else.
Promoter shares pledged🔒 In the app
Promoter shares given as collateral for loans; a high share is a risk to watch.
Holding trend🔒 In the app
Whether promoters, foreign funds and mutual funds have been adding or selling over recent quarters.

What do analysts say about Avenue Supermarts?

32 analysts cover Avenue Supermarts, and the consensus is hold. A consensus is a count of opinions, not a forecast; read it beside the numbers.

Analyst consensus

32 analysts
ConsensusHold
The rating most covering analysts give the share.
Average target price🔒 In the app
The mean of the analysts' 12-month price targets.
Upside to target🔒 In the app
How far the target sits above or below today's price.
Share rating it a buy🔒 In the app
The share of covering analysts with a buy rating.

What does Avenue Supermarts do and what is it sensitive to?

Avenue Supermarts Limited (DMart) is a national supermarket chain focused on value retailing, selling Foods, Non-Foods (FMCG) and General Merchandise & Apparel through its stores. Sensitive to: competitive intensity and pricing pressure.

Business-model card

FY2025 · 37 verified
2Revenue
4Channels
1Regulators
3Reg. dependencies
6Sensitivities
6Costs
2Geographies

Avenue Supermarts Limited (DMart) is a national supermarket chain focused on value retailing, selling Foods, Non-Foods (FMCG) and General Merchandise & Apparel through its stores. It earns by selling goods to customers at everyday low prices, with revenue recognised when control of the goods passes to the customer.

Revenue engine

2 verified
Foods (groceries, staples, processed foods, dairy, frozen products, beverages, confectionery, fruits and vegetables) (57.7%)
Largest category by revenue, sold through the company's stores as everyday-use items. Interpretation: the 57.73% FY 2024-25 share sits in the same category table block as this Foods description.
Non-Foods (FMCG) (home care, personal care, toiletries and other over-the-counter products) (20.0%)
Sold through stores as everyday household and personal care items. Interpretation: the 20.01% share is taken from the category table in the same block.

Customers & channels

4 verified
Retail customers across income groups buying daily-need goods
Value for money is stated as the main factor in daily purchase decisions across income groups, and most products are essential rather than discretionary.
DMart Ready alternate (delivery) channel
Company describes DMart Ready as a way to serve changing customer preferences through an alternate channel, alongside its stores.
Customer concentration
No single customer is 10% or more of revenue, so revenue is spread across a retail customer base. Interpretation: this follows from the retail sales model rather than from any named customer.
1 more statement
Cash-and-carry payment model
Sales are primarily cash and carry, so receivable credit risk is described as not significant. Sales to subsidiaries are also mentioned.

Regulators

1 verified
Goods & Service Tax regime
Indirect tax collected on sales and deducted from gross sales to arrive at reported revenue. Interpretation: a change in GST rates or treatment would change reported revenue, though the excerpt does not name the authority.

Regulatory dependencies

3 verified
Climate-related regulation
Changes in climate regulation are flagged as a cost driver. Interpretation: a stricter regime would raise compliance cost and reduce operating margin.
Regulatory approvals for store property
Store expansion depends on commercially viable properties, sale deeds, leave and licence registrations and regulatory approvals. Interpretation: delay in approvals would slow new store additions and therefore revenue growth.
Low-carbon transition rules
Shift to a low-carbon economy could bring new climate regulations. Interpretation: higher compliance cost and changes to how the business is run would hit cost lines.

Sensitivities

6 verified
Competitive intensity and pricing pressure
Higher competition or pricing pressure from existing and new retailers would hurt margins and volume. Interpretation: the company's strategy rests on everyday low prices, so pressure on price directly affects its distinct advantage.
Monsoon and commodity prices
A normal monsoon and easing commodity prices are said to support private consumption. Interpretation: a poor monsoon or rising commodity prices would be expected to weigh on consumption.
Interest rates
Easing interest rates are expected to support economic stability. Interpretation: higher rates would be expected to weigh on consumer spending.
3 more statements
Extreme weather and climate change
Extreme weather could disrupt store operations and climate change could lower sales and profits. Interpretation: higher weather disruption would reduce store revenue and raise costs.
Pandemic outbreak
A pandemic is named as a risk that could materially and adversely affect business and results. Interpretation: a pandemic would reduce store footfall and sales.
Foreign exchange
No derivatives were entered into and unhedged foreign currency exposure is nil at year end. Interpretation: FX movements have no stated direct effect on the reported position.

Cost inputs

6 verified
Contract labour charges
Largest operating expense line in the notes, rising from 944.34 to 1,259.36 crore. Interpretation: labour is supplied largely on contract, so labour cost rises with store operations.
Contract and permanent workforce
Store operations rely on a large contractual workforce alongside permanent staff. Interpretation: the contractual share drives labour cost sensitivity.
Electricity and fuel charges
Utility cost for stores, rising from 351.65 to 418.03 crore. Interpretation: energy price and store-count growth drive this line.
3 more statements
Procurement and distribution
Company consolidates buying and transport through distribution centres rather than small-lot vendor deliveries. Interpretation: distribution network costs are a key input line.
Related-party purchases
Purchases from related parties are a stated share of total purchases. Interpretation: related-party sourcing is a material purchase channel.
Lease costs for store premises
Lease interest on store premises rose from 43.42 to 56.06 crore. Interpretation: leased stores create a fixed financing-type cost.

Geographies

2 verified
India (domestic states and union territory)
Sole market: stores across 10 states, 1 union territory and the NCR, with Maharashtra, Gujarat and Telangana listed first. Interpretation: all revenue is domestic.
No export markets
No goods or services are exported, so the business has no international revenue.
Each statement is checked word for word against the FY2025 annual report; the passages are in the app.

What changed recently?

Q2 FY2027 results filed (10 Oct 2026).

Change log

8 entries · newest first
  1. Results filedQ2 FY2027 results filed.
  2. Results filedQ1 FY2027 results filed.
  3. Results filedQ4 FY2026 results filed.
  4. Results filedQ3 FY2026 results filed.
  5. Results filedQ2 FY2026 results filed.
  6. Results filedQ1 FY2026 results filed.
  7. Results filedQ4 FY2025 results filed.
  8. Corporate actionAnnual General Meeting.
Get alerts →Sign in to be told when any of these change.

What this page does not tell you

What could not be judged, and why. Never empty.
  • Models not runFair value, EPV, Graham number, Graham value, Lynch, Owner earnings: no valuation stored.
  • FlagsWATCH on 30 of 30 flags judged; 2 red.
  • Data gapsDividend yield, Business quality: not available yet.

What this page rests on

✓10 years of annual statements, through FY2026 (Mar-26)✓10 quarters of results✓113 months of month-end prices, adjusted for bonuses and splits○no valuation of ours yet✓business-model card FY2025 · 37 verified

Questions people ask

What is Avenue Supermarts's share price today?

Avenue Supermarts last traded at ₹3,364.90 on the NSE, as of 12 Oct 2026, 11:00 pm IST, down 4.3% on the day, down 16.3% over a year. Its 52-week range is ₹3,351 to ₹4,644. The live price is in the app.

What is Avenue Supermarts's market cap?

Avenue Supermarts's market capitalisation is about ₹2.29 lakh crore: what it would cost to buy every share at today's price. That makes it the 38th largest large cap company we cover.

Is Avenue Supermarts Ltd a large cap, mid cap or small cap?

Avenue Supermarts Ltd (DMART) is a large cap company in AMFI's classification for Jan-Jun 2026. SEBI's buckets go by rank on six-month average market capitalisation: the top 100 are large caps, 101 to 250 mid caps, the rest small caps.

What is Avenue Supermarts Ltd's P/E ratio?

73.51, vs peers 131.5 · 3rd of 7. Price divided by last year's earnings per share: how many years of today's profit you pay for.

Is Avenue Supermarts Ltd overvalued?

Fair, with low confidence: no valuation within 120 days; P/E 73.5 vs peers 131 (3rd of 7); P/B 10.1 vs peers 6.6 (8th of 10).

How does Avenue Supermarts Ltd make money?

Avenue Supermarts Limited (DMart) is a national supermarket chain focused on value retailing, selling Foods, Non-Foods (FMCG) and General Merchandise & Apparel through its stores. It earns by selling goods to customers at everyday low prices, with revenue recognised when control of the goods passes to the customer.

Who are Avenue Supermarts Ltd's peers?

Compared with 9 Retailing (the industry, as the basic industry was too small): Eternal Ltd, Trent Ltd, Lenskart Solutions Ltd, Meesho Ltd, FSN E-Commerce Ventures Ltd and 4 more. The app shows how they compare on every figure.

Is this investment advice?

No. Valarth is a research and learning tool and is not a SEBI-registered investment adviser or research analyst. The figures come from the company's filings and the exchanges; what to do with them is your call.

How did Avenue Supermarts do last quarter?

Avenue Supermarts reported revenue of ₹19,644 Cr, up 15.9% on a year earlier and a net profit of ₹743 Cr, up 9.7% in the Jun 2026 quarter.

Who owns Avenue Supermarts?

Avenue Supermarts is held by promoters 74.5%, foreign institutions 9.2%, domestic institutions 8.7%.

What do analysts say about Avenue Supermarts?

32 analysts cover Avenue Supermarts, and the consensus is hold. A consensus is a count of opinions, not a forecast; read it beside the numbers.

Everything on Avenue Supermarts, and 6,621 other companies, with 212 filters and the full peer tables