VALARTH See Hindalco Industries in the appOpen in app
HINDALCO · NSE · Aluminium

Hindalco Industries Ltd

What the numbers mean, from its filings and the exchange. Data as of 12 Oct 2026.
Large Cap · AMFI list Jan-Jun 2026 · Vendor sector: Basic Materials
cheap low confidence No valuation within 120 days; P/E 12.2 vs peers 15.0 (5th of 11); P/B 2.6 vs peers 3.2 (5th of 11).
Statements through FY2026Prices adjusted for corporate actionsNot yet reviewed by the adversarial model

What is Hindalco Industries's share price today?

Hindalco Industries last traded at ₹882.50 on the NSE, as of 12 Oct 2026, 11:00 pm IST, down 2.0% on the day, up 16.9% over a year. Its 52-week range is ₹754 to ₹1,176. The live price is in the app.

₹882.50 −2.0% today
+16.9% over 1 year · NSE, as of 12 Oct 2026, 11:00 pm IST
60 month-end closes, 31 Oct 2021 to 30 Sep 2026, adjusted for splits and bonuses
52-week range30% of the way up
Low ₹754High ₹1,176

What is Hindalco Industries's market cap?

Hindalco Industries's market capitalisation is about ₹2.02 lakh crore: what it would cost to buy every share at today's price. That makes it the 43rd largest large cap company we cover.

₹2.0 L Cr Large Cap43rd largest large cap company
Large Cap means the 100 largest listed companies, under SEBI's rules. Shares in issue are worked out from the market cap and the price. What market cap tells you →

Key facts

From the exchange
Symbol
NSE: HINDALCO
ISIN
INE038A01020
Cap bucket
Large Cap, 43rd largest by market cap
Industry (NSE)
Commodities › Metals & Mining › Non - Ferrous Metals › Aluminium
Listed since
1997
Futures and options
Traded

Is Hindalco Industries overvalued?

Cheap, with low confidence: no valuation within 120 days; P/E 12.2 vs peers 15.0 (5th of 11); P/B 2.6 vs peers 3.2 (5th of 11).

Valuation

Latest price and trailing 12 months
P/E 12.19
vs peers 15.0 · 5th of 11
Price divided by last year's earnings per share: how many years of today's profit you pay for. Learn more →
P/B 2.56
vs peers 3.2 · 5th of 11
Price divided by book value per share: what you pay for each rupee of net assets on the balance sheet. Learn more →
Market cap ₹2.02 lakh Cr
Total market value of all shares, in ₹ crore. Learn more →
Dividend yield 0.6%
vs peers 2.0% · 8th of 10
Last year's dividends as a share of today's price. Learn more →
PEG (vendor) Not available
P/E divided by the vendor's earnings growth figure, which it does not disclose; a P/E adjusted for how fast profits grow. Learn more →
PEG on our 3-year EPS growth 1.21
P/E divided by the 3-year EPS growth rate from the stored accounts. Learn more →
3 models could be judged
Skipped — Fair value, EPV, Graham number, Graham value, Lynch, Owner earnings: no valuation stored

Our valuation range

🔒 Pro
Value range, implied growth at today's price, and the nine models behind it: in the app.

Is Hindalco Industries a quality business?

Quality score 41.1, 8th of 11 in its peer set; CAUTION on 30 of 30 flags judged.

Quality and risk

Data as of 12 Oct 2026
Business quality Not available
The kind of business, which sets the yardstick it is judged by. Learn more →
Quality score 41.1
vs peers 46.4 · 8th of 11
Returns, margins, leverage and consistency against its peers, out of 100. Learn more →
Risk level CAUTION
30 of 30 flags judged
From flags on debt, earnings quality, dilution and price swings. Learn more →

Profitability

ROE 13.7%
vs peers 16.8% · 7th of 11
Return on equity: profit as a share of shareholders' money. Learn more →
ROCE 16.7%
vs peers 14.6% · 6th of 11
Return on capital employed: operating profit as a share of all the capital in the business, debt and equity. Learn more →
Profit margin 5.5%
vs peers 15.3% · 8th of 11
Profit after everything, as a share of revenue. Learn more →
EPS ₹60.32
Trailing 12 months
Profit for each share over the last 12 months.

Scorecard

🔒 Pro
Health scores and red flags with their values and history: in the app.
Inside the app

Get a sneak peek of Valarth

Start freeStart free
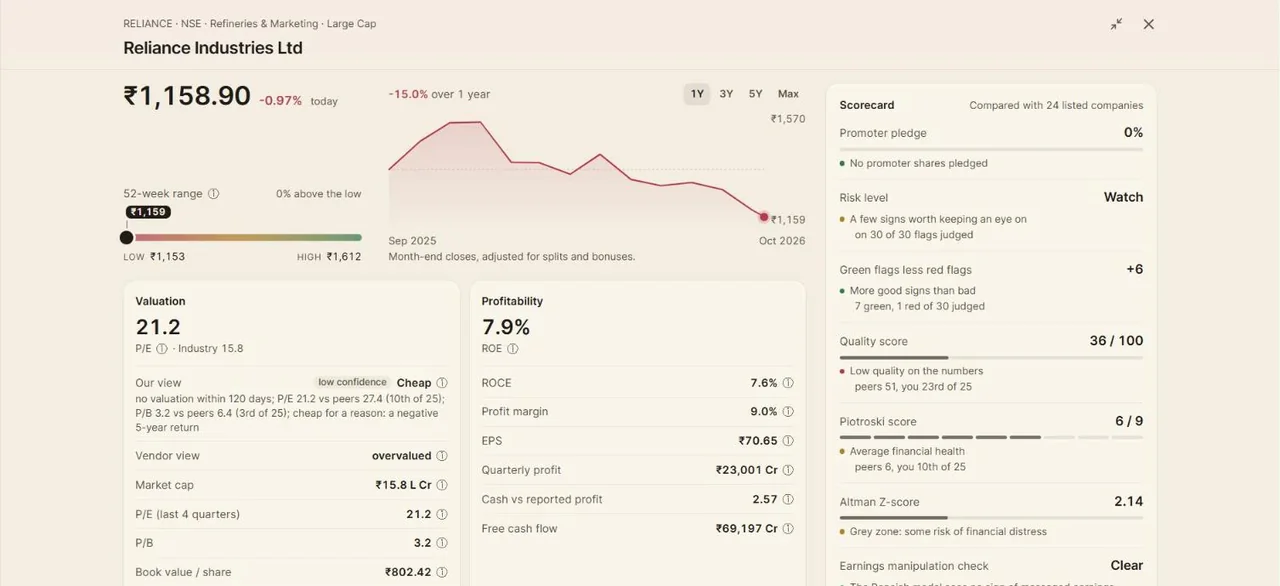
A Valarth stock page: the share price with its chart and 52-week range, valuation and profitability figures, and a scorecard of health checks.
Stock pagePrice, valuation, profitability and a scorecard of health checks for every company, each figure explained.
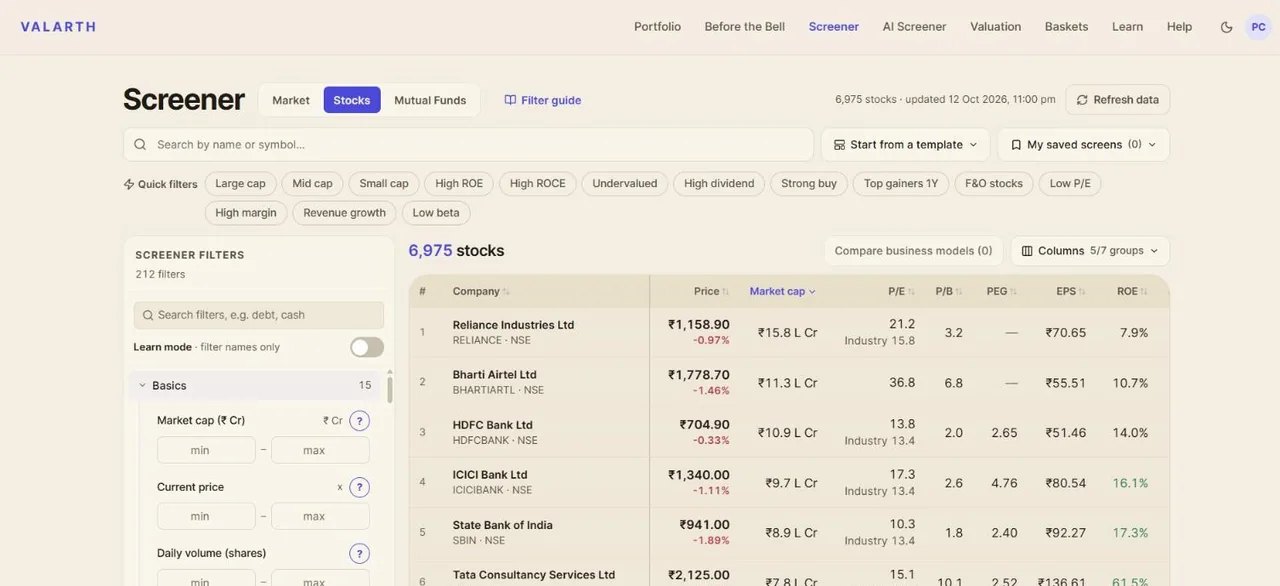
The Valarth stock screener: a table of companies with price, market cap, P/E, P/B, PEG, EPS and ROE, and filters down the left.
ScreenerEvery listed company, filtered on 212 figures, each with a plain-language lesson beside it.
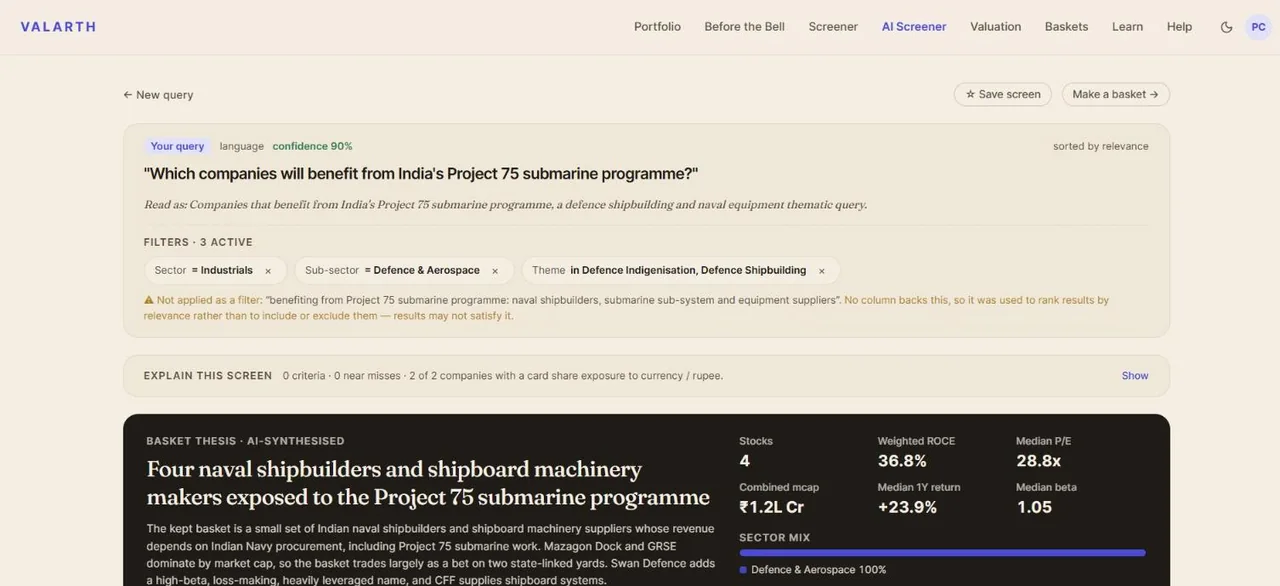
The Valarth AI Screener answering 'Which companies will benefit from India's Project 75 submarine programme?' with a basket of four naval shipbuilders and a written thesis.
AI ScreenerAsk a question in plain English, like which companies benefit from India's Project 75. It reads the intent, builds the screen and writes the thesis.
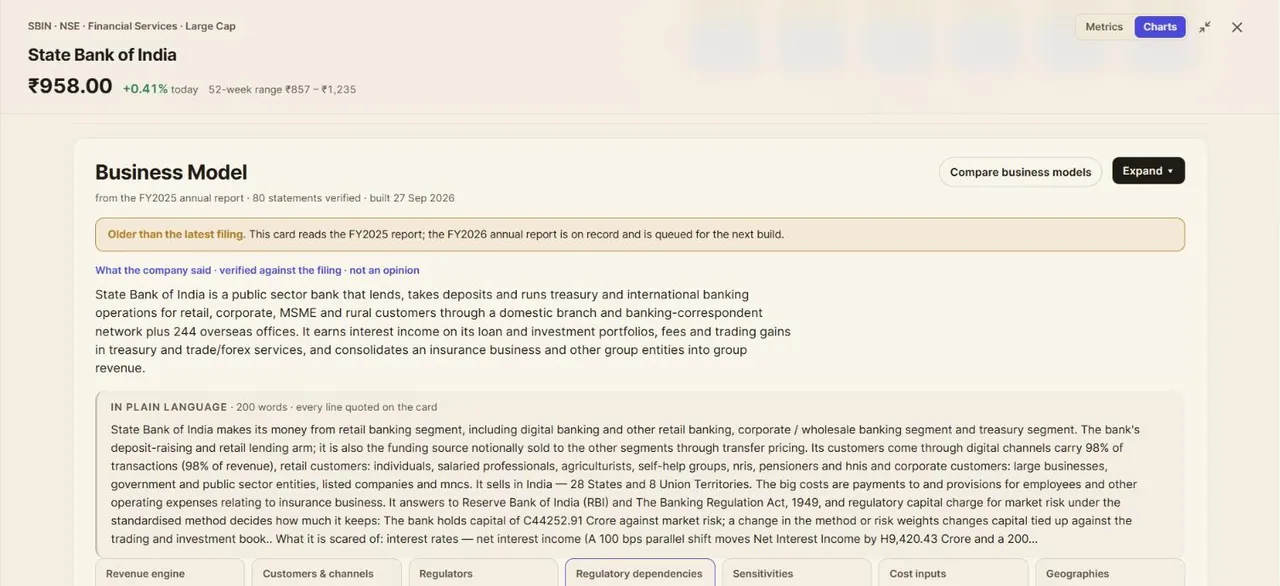
A Valarth business-model card for State Bank of India, with a plain-language summary and statements verified against the filing.
Business modelHow a company makes money and what can hurt it, each statement checked against its annual report.
Valarth's Before the Bell edition, with the day's headline, regulator notes and sector moves.
Before the BellA morning edition before the market opens: what moved, which rule changed, and what it means for your holdings.

Has Hindalco Industries made money for shareholders?

Yes: +16.9% over one year and +14.1% a year over five years.

Shareholder returns

1-year return +16.9%
Price only
What the share price did over the last 12 months. Learn more →
5-year return +14.1% a year
Price only
Yearly average price return over five years, bonuses and splits adjusted. Learn more →
Wealth destroyer No
Five-year total return — price CAGR on bonus- and split-adjusted closes plus the dividend yield — below the 7% a bank fixed deposit paid. Learn more →

Returns

3Y and 5Y are yearly averages
1W
−4.0%
1M
−6.1%
3M
−6.9%
6M
−8.0%
1Y
+16.9%
3Y
+27.0%
5Y
+14.1%

Does Hindalco Industries pay a dividend?

Yes. Hindalco Industries's dividend yield is 0.56% at the latest price; the last payout was ₹5.00 a share, ex-dividend 10 Jul 2026.

Dividends

Per share, by ex-dividend date
Dividend yield0.56%
The past 12 months' dividends as a share of today's price.
10 Jul 2026 · Final₹5.00
8 Aug 2025 · Final₹5.00
9 Aug 2024 · Final₹3.50
14 Aug 2023 · Final₹3.00
11 Aug 2022 · Final₹4.00
Payout ratio🔒 In the app
The share of profit paid out as dividends; a very high share leaves little to reinvest.
Dividend growth, 5 years🔒 In the app
How fast the dividend per share has grown a year.
Years without a miss🔒 In the app
How many years in a row a dividend has been paid.

Is Hindalco Industries growing?

Revenue 3 years 7.4% a year; profit 3 years 9.9% a year; revenue 5 years 8.7% a year.

Growth

Statements through FY2026 (Mar-26)
Revenue 3 years 7.4% a year
vs peers 6.1% · 4th of 11
Compound annual growth of revenue over three years. Learn more →
Profit 3 years 9.9% a year
vs peers 14.7% · 7th of 10
Compound annual growth of net profit over three years. Learn more →
Revenue 5 years 8.7% a year
Compound annual growth of revenue over five years. Learn more →
Profit 5 years 3.6% a year
Compound annual growth of net profit over five years. Learn more →
EPS 3 years 10.1% a year
Growth in earnings per share, so dilution counts against the company. Learn more →
EPS 5 years 30.8% a year
Growth in earnings per share over five years, so dilution counts against the company. Learn more →
P/E vs own history 25.9%
vs peers -4.7% · 9th of 10
Today's P/E against its own 5-year median; negative is cheaper than its history. Learn more →

How did Hindalco Industries do last quarter?

Hindalco Industries reported revenue of ₹84,825 Cr, up 15.3% on a year earlier and a net profit of ₹7,013 Cr, down 16.3% in the Jun 2026 quarter.

Latest quarter

Jun 2026
Revenue, latest quarter₹84,825 Cr
+15.3% on a year earlier
What the company took in over the quarter.
Net profit, latest quarter₹7,013 Cr
−16.3% on a year earlier
What was left for shareholders after every cost and tax.

How does Hindalco Industries compare with its peers?

Compared with 11 Metals & Mining (the sector, as the industry was too small); 5th of 11 on P/E; 8th of 11 on quality score.

Compared with 11 Metals & Mining (the sector, as the industry was too small)

11 companies

Hindalco Industries against its peers

Largest 10 of 11 peers, by market cap
CompanyMarket capP/EP/BROEROCE1YQuality 🔒Rank 🔒
Hindalco Industries Ltd₹2.0 L Cr12.22.613.7%16.7%+16.9%
JSW Steel Ltd₹2.9 L Cr11.54.07.9%9.9%+0.6%
Hindustan Zinc Ltd₹2.3 L Cr13.59.476.7%66.1%+7.5%
Tata Steel Ltd₹2.2 L Cr19.61.49.7%11.0%+0.5%
Vedanta Aluminium Metal Ltd₹1.5 L Cr————−25.1%
Jindal Steel Ltd₹1.0 L Cr38.02.18.1%10.7%+0.9%
Vedanta Ltd₹1.0 L Cr9.63.317.3%2.0%−44.9%
Lloyds Metals & Energy Ltd₹1.0 L Cr20.66.135.1%35.8%+37.8%
Steel Authority of India Ltd₹70,859 Cr16.61.16.6%7.3%+29.5%
NMDC Ltd₹63,125 Cr8.52.023.4%26.4%−6.9%
Jindal Stainless Ltd₹58,455 Cr18.03.116.2%18.3%−8.4%
Peer median—15.03.216.8%14.6%+0.6%
Market cap in rupees crore; P/E and P/B on the latest price; 1Y is the price return over a year. A dash is a figure that does not apply or is not reported.

Full peer comparison

🔒 Pro
Every peer, every figure, the ranks and the quality and forensic scores side by side: in the app.

Who owns Hindalco Industries?

Hindalco Industries is held by promoters 34.7%, foreign institutions 35.6%, domestic institutions 19.9%.

Shareholding pattern

Latest filing, percent of shares
Promoters34.7%
The founders and controlling group.
Foreign institutions35.6%
Overseas funds investing through the FPI route.
Domestic institutions19.9%
Indian insurers, banks, pension and mutual funds together.
Mutual funds10.1%
Indian mutual fund schemes; part of domestic institutions.
Retail and others5.0%
Individual investors and everyone else.
Promoter shares pledged🔒 In the app
Promoter shares given as collateral for loans; a high share is a risk to watch.
Holding trend🔒 In the app
Whether promoters, foreign funds and mutual funds have been adding or selling over recent quarters.

What do analysts say about Hindalco Industries?

30 analysts cover Hindalco Industries, and the consensus is buy. A consensus is a count of opinions, not a forecast; read it beside the numbers.

Analyst consensus

30 analysts
ConsensusBuy
The rating most covering analysts give the share.
Average target price🔒 In the app
The mean of the analysts' 12-month price targets.
Upside to target🔒 In the app
How far the target sits above or below today's price.
Share rating it a buy🔒 In the app
The share of covering analysts with a buy rating.

What does Hindalco Industries do and what is it sensitive to?

Hindalco sells aluminium and copper products: Novelis rolled and recycled aluminium, upstream and downstream aluminium, and copper cathode, rods and related products, mainly to industrial customers. Sensitive to: copper, aluminium and other input prices.

Business-model card

FY2025 · 44 verified
4Revenue
4Channels
3Regulators
4Reg. dependencies
4Sensitivities
5Costs
4Geographies

Hindalco sells aluminium and copper products: Novelis rolled and recycled aluminium, upstream and downstream aluminium, and copper cathode, rods and related products, mainly to industrial customers. It earns through metal sales whose final prices are often set off external benchmarks such as LME, with derivatives used to manage the timing and currency gap between input and output prices.

Revenue by segment

year ended March 31, 2025 (consolidated; segment revenue column before inter-segment elimination)
Novelis57.8%
Aluminium Upstream15.3%
Aluminium Downstream5.1%
Copper21.8%

Revenue engine

4 verified
Subsidiary Novelis Inc (Novelis segment): aluminium rolling and recycling
Novelis segment revenue is measured under US GAAP and reported as Novelis revenue from external customers; Novelis is described as a leading aluminium rolling and recycling business. Interpretation: this is the largest revenue line in the consolidated segment table by external revenue.
Copper business (copper cathode, copper rods, precious metals, DAP) (58.0%)
Copper segment covers copper cathode, copper rods, precious metals and di-ammonium phosphate (DAP). Share is the entity-level turnover split from the standalone products table (copper 58%, aluminium 42%); it is not the consolidated split.
Aluminium upstream (primary aluminium and related metal) (42.0%)
Vertically integrated aluminium business; input and output pricing are on different benchmarks, so the company may hedge each separately. Entity-level aluminium share is 42% of turnover per the standalone table.
1 more statement
Aluminium downstream (flat rolled products, extrusion, foils)
Value-added aluminium products sold as flat rolled products, extrusions and foils, reported as a separate segment with different risks and returns.

Customers & channels

4 verified
Single external customer above 10% of Group revenue (attributed to Novelis)
Revenue concentration: one external customer exceeded 10% of Group revenue from operations in the current year, attributed to the Novelis segment. Interpretation: amount stated as Rs 24,584 Crore.
Dealers and distributors (16.1%)
Share of total sales to dealers/distributors was 16.10% in FY 2024-25 (20.20% prior year), with 1,198 dealers/distributors; top 10 took 69.41% of dealer sales.
Long-term customer contracts (company SWOT)
Company states it has a strong customer base with long-term contracts, which supports volume visibility for the Novelis business. Interpretation: contract terms and pricing mechanisms are not given in the excerpt.
1 more statement
Customer engagement through zonal customer meets
Structured customer engagement includes annual or bi-annual customer meets in every zone, plus technical services and value selling for sales staff. Relevant to repeat orders from industrial buyers.

Regulators

3 verified
Ministry-administered authority under the Mines and Minerals (Regulation and Development) Act, 1957
Act is listed among laws whose compliance was verified on a test-check basis for the company, governing mining operations that feed its metal inputs.
Legal Metrology Act, 2009
Listed among laws whose compliance was verified on a test-check basis; governs measurement and sale quantities for products sold.
Mines Act, 1952
Listed among laws whose compliance was verified on test-check basis; governs safety and operation of mines supplying the company.

Regulatory dependencies

4 verified
Carbon pricing and EU CBAM
Interpretation: a carbon price or CBAM charge would raise operating costs on exports to the EU; the excerpt says such policies may influence operational costs in the future.
Government export incentives
Export-related government grants and incentives are recognised within revenue; a reduction would lower revenue and margin on export sales.
Nutrient subsidy on DAP sold to farmers
Revenue includes nutrient-based subsidy from the Government of India on DAP sales; a change in subsidy would move copper-segment revenue on DAP.
1 more statement
Trade tariffs and retaliatory measures
Interpretation: tariffs that cut global trade volumes would reduce export demand for the company's rolled and copper products and affect trade-linked pricing.

Sensitivities

4 verified
Copper, aluminium and other input prices
Lower copper prices, stronger USD/INR and higher input prices (coal, furnace oil, natural gas) are stated as the major price risks that adversely affect the business.
USD/INR exchange rate for aluminium
Direction: when INR strengthens against USD, aluminium profitability falls; when INR weakens, profitability benefits, because aluminium costs are mainly in INR.
Floating-rate interest rates
A 100 bps rise in rates on floating-rate borrowings reduces post-tax profit by Rs 47 Crore in FY 2024-25 (Rs 62 Crore prior year); a fall has an equal and opposite effect.
1 more statement
Geopolitical and trade-policy disruption
Dependence on global supply chains and exposure to geopolitical issues, trade policies or natural disasters are listed as weaknesses; disruption would raise supply costs or delay shipments.

Cost inputs

5 verified
Power and fuel expenses (consolidated)
Consolidated power and fuel expense was Rs 14,399 Crore in FY 2024-25 (Rs 14,481 Crore prior year), net of Rs 3 Crore transferred to capital work-in-progress.
Purchases from trading houses (43.2%)
Trading houses supplied 43.23% of purchases in FY 2024-25 (46.92% prior year); 26 trading houses, with the top 10 accounting for 90.69% of trading-house purchases.
Related-party purchases (10.0%)
Purchases from related parties were 9.99% of total purchases in FY 2024-25, up from 6.93% prior year.
2 more statements
Raw materials from third-party suppliers
Company lists reliance on third-party suppliers for metal and non-metal raw materials as a weakness; supply shortfalls or price changes pass through to cost of goods.
Aluminium imports including scrap
Total imports including scrap were about 3.0 million tonnes in FY 2024-25, up from about 2.7 million tonnes in FY 2023-24.

Geographies

4 verified
Global operations footprint
Company operates across 10 countries with 50 established units in aluminium and copper; Novelis facilities are across North America, Europe, Asia and South America.
Export share of entity turnover (18.0%)
Exports were stated as 18% of the entity's total turnover, per the standalone disclosure.
Revenue by customer country (group)
External revenue from customers in the United States was Rs 55,063 Crore, Brazil Rs 20,239 Crore and South Korea Rs 9,243 Crore in FY 2024-25; total outside India was Rs 160,492 Crore.
1 more statement
India plants and offices (standalone)
Standalone operations include 16 plants and 1 office in India across 11 states; no international plants reported at standalone level.
Each statement is checked word for word against the FY2025 annual report; the passages are in the app.

What changed recently?

Q1 FY2027 results filed (7 Aug 2026).

Change log

8 entries · newest first
  1. Results filedQ1 FY2027 results filed.
  2. Corporate actionDividend - Rs 5 Per Share.
  3. Results filedQ4 FY2026 results filed.
  4. Results filedQ3 FY2026 results filed.
  5. Results filedQ2 FY2026 results filed.
  6. Results filedQ1 FY2026 results filed.
  7. Corporate actionDividend - Rs 5 Per Share.
  8. Results filedQ4 FY2025 results filed.
Get alerts →Sign in to be told when any of these change.

What this page does not tell you

What could not be judged, and why. Never empty.
  • Models not runFair value, EPV, Graham number, Graham value, Lynch, Owner earnings: no valuation stored.
  • FlagsCAUTION on 30 of 30 flags judged; 3 red.
  • Data gapsPEG (vendor), Business quality: not available yet.

What this page rests on

✓10 years of annual statements, through FY2026 (Mar-26)✓10 quarters of results✓230 months of month-end prices, adjusted for bonuses and splits○no valuation of ours yet✓business-model card FY2025 · 44 verified

Questions people ask

What is Hindalco Industries's share price today?

Hindalco Industries last traded at ₹882.50 on the NSE, as of 12 Oct 2026, 11:00 pm IST, down 2.0% on the day, up 16.9% over a year. Its 52-week range is ₹754 to ₹1,176. The live price is in the app.

What is Hindalco Industries's market cap?

Hindalco Industries's market capitalisation is about ₹2.02 lakh crore: what it would cost to buy every share at today's price. That makes it the 43rd largest large cap company we cover.

Is Hindalco Industries Ltd a large cap, mid cap or small cap?

Hindalco Industries Ltd (HINDALCO) is a large cap company in AMFI's classification for Jan-Jun 2026. SEBI's buckets go by rank on six-month average market capitalisation: the top 100 are large caps, 101 to 250 mid caps, the rest small caps.

What is Hindalco Industries Ltd's P/E ratio?

12.19, vs peers 15.0 · 5th of 11. Price divided by last year's earnings per share: how many years of today's profit you pay for.

Is Hindalco Industries Ltd overvalued?

Cheap, with low confidence: no valuation within 120 days; P/E 12.2 vs peers 15.0 (5th of 11); P/B 2.6 vs peers 3.2 (5th of 11).

How does Hindalco Industries Ltd make money?

Hindalco sells aluminium and copper products: Novelis rolled and recycled aluminium, upstream and downstream aluminium, and copper cathode, rods and related products, mainly to industrial customers. It earns through metal sales whose final prices are often set off external benchmarks such as LME, with derivatives used to manage the timing and currency gap between input and output prices.

Who are Hindalco Industries Ltd's peers?

Compared with 11 Metals & Mining (the sector, as the industry was too small): JSW Steel Ltd, Hindustan Zinc Ltd, Tata Steel Ltd, Vedanta Aluminium Metal Ltd, Jindal Steel Ltd and 6 more. The app shows how they compare on every figure.

Is this investment advice?

No. Valarth is a research and learning tool and is not a SEBI-registered investment adviser or research analyst. The figures come from the company's filings and the exchanges; what to do with them is your call.

How did Hindalco Industries do last quarter?

Hindalco Industries reported revenue of ₹84,825 Cr, up 15.3% on a year earlier and a net profit of ₹7,013 Cr, down 16.3% in the Jun 2026 quarter.

Who owns Hindalco Industries?

Hindalco Industries is held by promoters 34.7%, foreign institutions 35.6%, domestic institutions 19.9%.

Does Hindalco Industries pay a dividend?

Yes. Hindalco Industries's dividend yield is 0.56% at the latest price; the last payout was ₹5.00 a share, ex-dividend 10 Jul 2026.

What do analysts say about Hindalco Industries?

30 analysts cover Hindalco Industries, and the consensus is buy. A consensus is a count of opinions, not a forecast; read it beside the numbers.

Everything on Hindalco Industries, and 6,621 other companies, with 212 filters and the full peer tables