VALARTH See Dr Reddys Laboratories in the appOpen in app
DRREDDY ยท NSE ยท Pharmaceuticals

Dr Reddys Laboratories Ltd

What the numbers mean, from its filings and the exchange. Data as of 12 Oct 2026.
Mid Cap ยท AMFI list Jan-Jun 2026 ยท Vendor sector: Basic Materials
cheap low confidence No valuation within 120 days; P/E 30.9 vs peers 42.8 (5th of 23); P/B 3.3 vs peers 7.2 (6th of 25).
Cheap for a reason: Profit -2.4% a year over 3 years, a negative 5-year return.
Statements through FY2026Prices adjusted for corporate actionsNot yet reviewed by the adversarial model

What is Dr Reddys Laboratories's share price today?

Dr Reddys Laboratories last traded at โ‚น1,229.40 on the NSE, as of 12 Oct 2026, 11:00 pm IST, up 2.7% on the day, down 5.2% over a year. Its 52-week range is โ‚น1,101 to โ‚น1,415. The live price is in the app.

โ‚น1,229.40 +2.7% today
โˆ’5.2% over 1 year ยท NSE, as of 12 Oct 2026, 11:00 pm IST
60 month-end closes, 31 Oct 2021 to 30 Sep 2026, adjusted for splits and bonuses
52-week range41% of the way up
Low โ‚น1,101High โ‚น1,415

What is Dr Reddys Laboratories's market cap?

Dr Reddys Laboratories's market capitalisation is about โ‚น99,911 crore: what it would cost to buy every share at today's price. That makes it the 16th largest mid cap company we cover.

โ‚น99,911 Cr Mid Cap16th largest mid cap company
Mid Cap means the companies ranked 101 to 250 by size, under SEBI's rules. Shares in issue are worked out from the market cap and the price. What market cap tells you โ†’

Key facts

From the exchange
Symbol
NSE: DRREDDY
ISIN
INE089A01031
Cap bucket
Mid Cap, 16th largest by market cap
Industry (NSE)
Healthcare โ€บ Pharmaceuticals & Biotechnology โ€บ Pharmaceuticals
Listed since
2003
Futures and options
Traded

Is Dr Reddys Laboratories overvalued?

Cheap, with low confidence: no valuation within 120 days; P/E 30.9 vs peers 42.8 (5th of 23); P/B 3.3 vs peers 7.2 (6th of 25). Cheap for a reason: profit -2.4% a year over 3 years, a negative 5-year return.

Valuation

Latest price and trailing 12 months
P/E 30.94
vs peers 42.8 ยท 5th of 23
Price divided by last year's earnings per share: how many years of today's profit you pay for. Learn more โ†’
P/B 3.32
vs peers 7.2 ยท 6th of 25
Price divided by book value per share: what you pay for each rupee of net assets on the balance sheet. Learn more โ†’
Market cap โ‚น99,911 Cr
Total market value of all shares, in โ‚น crore. Learn more โ†’
Dividend yield 0.6%
vs peers 0.3% ยท 8th of 19
Last year's dividends as a share of today's price. Learn more โ†’
PEG (vendor) Not available
P/E divided by the vendor's earnings growth figure, which it does not disclose; a P/E adjusted for how fast profits grow. Learn more โ†’
PEG on our 3-year EPS growth Not available
P/E divided by the 3-year EPS growth rate from the stored accounts. Learn more โ†’
3 models could be judged
Skipped โ€” Fair value, EPV, Graham number, Graham value, Lynch, Owner earnings: no valuation stored

Our valuation range

๐Ÿ”’ Pro
Value range, implied growth at today's price, and the nine models behind it: in the app.

Is Dr Reddys Laboratories a quality business?

Quality score 26.5, 21st of 24 in its peer set; WATCH on 30 of 30 flags judged.

Quality and risk

Data as of 12 Oct 2026
Business quality Not available
The kind of business, which sets the yardstick it is judged by. Learn more โ†’
Quality score 26.5
vs peers 53.7 ยท 21st of 24
Returns, margins, leverage and consistency against its peers, out of 100. Learn more โ†’
Risk level WATCH
30 of 30 flags judged
From flags on debt, earnings quality, dilution and price swings. Learn more โ†’

Profitability

ROE 10.7%
vs peers 16.2% ยท 20th of 25
Return on equity: profit as a share of shareholders' money. Learn more โ†’
ROCE 12.6%
vs peers 19.0% ยท 21st of 25
Return on capital employed: operating profit as a share of all the capital in the business, debt and equity. Learn more โ†’
Profit margin 9.3%
vs peers 14.8% ยท 22nd of 24
Profit after everything, as a share of revenue. Learn more โ†’
EPS โ‚น49.79
Trailing 12 months
Profit for each share over the last 12 months.

Scorecard

๐Ÿ”’ Pro
Health scores and red flags with their values and history: in the app.
Inside the app

Get a sneak peek of Valarth

Start freeStart free
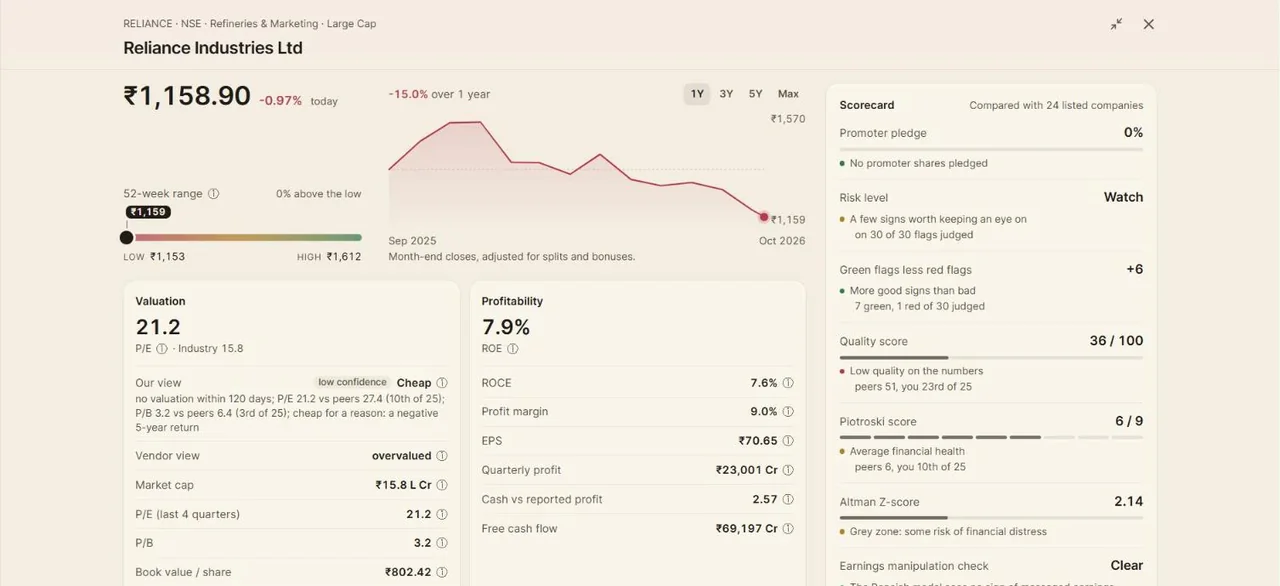
A Valarth stock page: the share price with its chart and 52-week range, valuation and profitability figures, and a scorecard of health checks.
Stock pagePrice, valuation, profitability and a scorecard of health checks for every company, each figure explained.
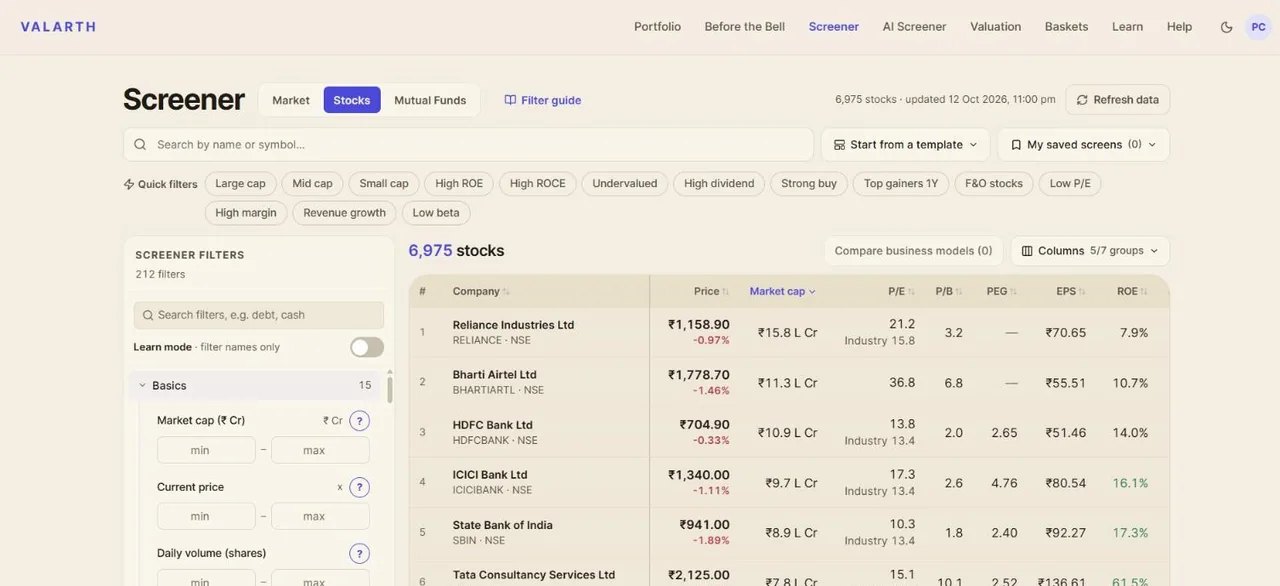
The Valarth stock screener: a table of companies with price, market cap, P/E, P/B, PEG, EPS and ROE, and filters down the left.
ScreenerEvery listed company, filtered on 212 figures, each with a plain-language lesson beside it.
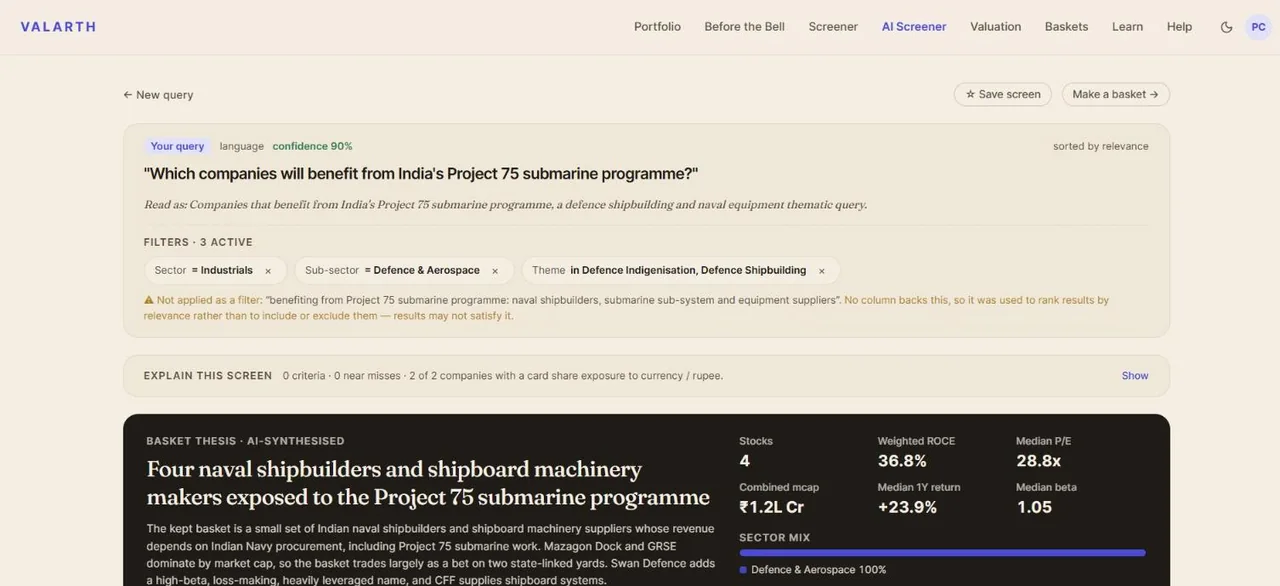
The Valarth AI Screener answering 'Which companies will benefit from India's Project 75 submarine programme?' with a basket of four naval shipbuilders and a written thesis.
AI ScreenerAsk a question in plain English, like which companies benefit from India's Project 75. It reads the intent, builds the screen and writes the thesis.
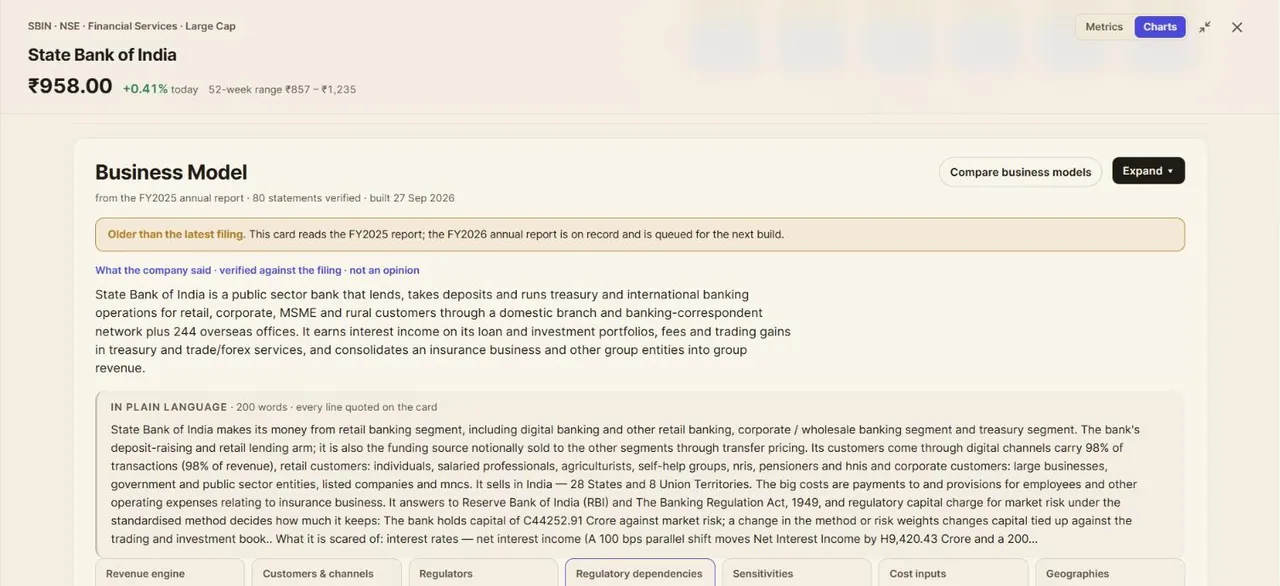
A Valarth business-model card for State Bank of India, with a plain-language summary and statements verified against the filing.
Business modelHow a company makes money and what can hurt it, each statement checked against its annual report.
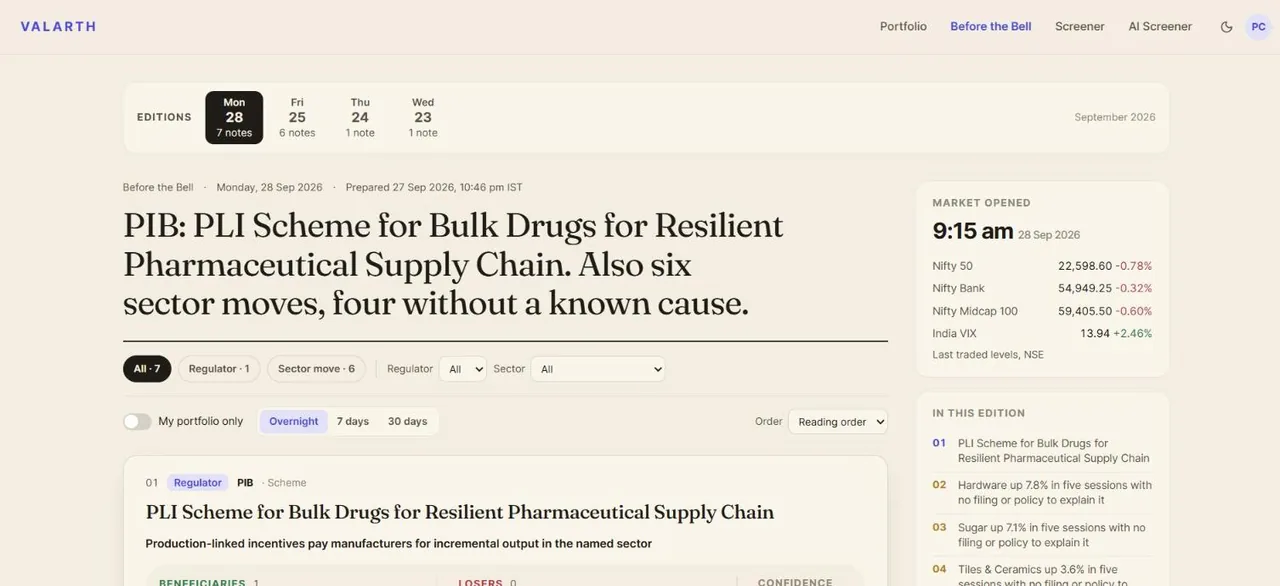
Valarth's Before the Bell edition, with the day's headline, regulator notes and sector moves.
Before the BellA morning edition before the market opens: what moved, which rule changed, and what it means for your holdings.

Has Dr Reddys Laboratories made money for shareholders?

Mixed: โˆ’5.2% over one year and +4.8% a year over five years.

Shareholder returns

1-year return โˆ’5.2%
Price only
What the share price did over the last 12 months. Learn more โ†’
5-year return +4.8% a year
Price only
Yearly average price return over five years, bonuses and splits adjusted. Learn more โ†’
Wealth destroyer Yes
Five-year total return โ€” price CAGR on bonus- and split-adjusted closes plus the dividend yield โ€” below the 7% a bank fixed deposit paid. Learn more โ†’

Returns

3Y and 5Y are yearly averages
1W
โˆ’0.5%
1M
+4.5%
3M
โˆ’3.0%
6M
โˆ’3.1%
1Y
โˆ’5.2%
3Y
+4.7%
5Y
+4.8%

Does Dr Reddys Laboratories pay a dividend?

Yes. Dr Reddys Laboratories's dividend yield is 0.64% at the latest price; the last payout was โ‚น8.00 a share, ex-dividend 10 Jul 2026.

Dividends

Per share, by ex-dividend date
Dividend yield0.64%
The past 12 months' dividends as a share of today's price.
10 Jul 2026 ยท Finalโ‚น8.00
10 Jul 2025 ยท Finalโ‚น8.00
16 Jul 2024 ยท Finalโ‚น8.00
11 Jul 2023 ยท Finalโ‚น8.00
11 Jul 2022 ยท Finalโ‚น6.00
The share of profit paid out as dividends; a very high share leaves little to reinvest.
Dividend growth, 5 years๐Ÿ”’ In the app
How fast the dividend per share has grown a year.
Years without a miss๐Ÿ”’ In the app
How many years in a row a dividend has been paid.

Is Dr Reddys Laboratories growing?

Revenue 3 years 10.8% a year; profit 3 years -2.4% a year; revenue 5 years 9.4% a year.

Growth

Statements through FY2026 (Mar-26)
Revenue 3 years 10.8% a year
vs peers 14.3% ยท 16th of 24
Compound annual growth of revenue over three years. Learn more โ†’
Profit 3 years -2.4% a year
vs peers 20.9% ยท 20th of 21
Compound annual growth of net profit over three years. Learn more โ†’
Revenue 5 years 9.4% a year
Compound annual growth of revenue over five years. Learn more โ†’
Profit 5 years 8.1% a year
Compound annual growth of net profit over five years. Learn more โ†’
EPS 3 years -2.4% a year
Growth in earnings per share, so dilution counts against the company. Learn more โ†’
EPS 5 years 16.4% a year
Growth in earnings per share over five years, so dilution counts against the company. Learn more โ†’
P/E vs own history 17.6%
vs peers 8.7% ยท 12th of 19
Today's P/E against its own 5-year median; negative is cheaper than its history. Learn more โ†’

How did Dr Reddys Laboratories do last quarter?

Dr Reddys Laboratories reported revenue of โ‚น8,070 Cr, up 3.2% on a year earlier and a net profit of โ‚น436 Cr, down 27.4% in the Jun 2026 quarter.

Latest quarter

Jun 2026
Revenue, latest quarterโ‚น8,070 Cr
+3.2% on a year earlier
What the company took in over the quarter.
Net profit, latest quarterโ‚น436 Cr
โˆ’27.4% on a year earlier
What was left for shareholders after every cost and tax.

How does Dr Reddys Laboratories compare with its peers?

Compared with 24 Pharmaceuticals; 5th of 23 on P/E; 21st of 24 on quality score.

Dr Reddys Laboratories against its peers

Largest 10 of 24 peers, by market cap
CompanyMarket capP/EP/BROEROCE1YQuality ๐Ÿ”’Rank ๐Ÿ”’
Dr Reddys Laboratories Ltdโ‚น99,911 Cr30.93.310.7%12.6%โˆ’5.2%
Divis Laboratories Ltdโ‚น2.5 L Cr84.89.416.5%21.4%+42.5%
Torrent Pharmaceuticals Ltdโ‚น1.8 L Cr74.316.927.3%19.2%+32.4%
Zydus Lifesciences Ltdโ‚น1.1 L Cr24.93.715.9%15.9%+12.3%
Laurus Labs Ltdโ‚น1.1 L Cr100.510.215.1%14.9%+132.9%
Cipla Ltdโ‚น1.1 L Cr31.22.910.6%13.9%โˆ’16.8%
Mankind Pharma Ltdโ‚น97,830 Cr47.95.013.3%13.1%โˆ’3.0%
Aurobindo Pharma Ltdโ‚น97,411 Cr26.43.311.2%12.9%+48.9%
Lupin Ltdโ‚น89,469 Cr15.83.523.4%27.5%โˆ’0.8%
Glenmark Pharmaceuticals Ltdโ‚น64,714 Cr36.02.53.9%6.3%+20.1%
Alkem Laboratories Ltdโ‚น63,118 Cr29.34.517.3%18.8%โˆ’3.9%
Peer medianโ€”42.87.216.2%19.0%+33.8%
Market cap in rupees crore; P/E and P/B on the latest price; 1Y is the price return over a year. A dash is a figure that does not apply or is not reported.

Full peer comparison

๐Ÿ”’ Pro
Every peer, every figure, the ranks and the quality and forensic scores side by side: in the app.

Who owns Dr Reddys Laboratories?

Dr Reddys Laboratories is held by promoters 26.6%, foreign institutions 32.1%, domestic institutions 31.7%.

Shareholding pattern

Latest filing, percent of shares
Promoters26.6%
The founders and controlling group.
Foreign institutions32.1%
Overseas funds investing through the FPI route.
Domestic institutions31.7%
Indian insurers, banks, pension and mutual funds together.
Mutual funds13.2%
Indian mutual fund schemes; part of domestic institutions.
Retail and others7.3%
Individual investors and everyone else.
Promoter shares pledged๐Ÿ”’ In the app
Promoter shares given as collateral for loans; a high share is a risk to watch.
Whether promoters, foreign funds and mutual funds have been adding or selling over recent quarters.

What do analysts say about Dr Reddys Laboratories?

36 analysts cover Dr Reddys Laboratories, and the consensus is hold. A consensus is a count of opinions, not a forecast; read it beside the numbers.

Analyst consensus

36 analysts
ConsensusHold
The rating most covering analysts give the share.
Average target price๐Ÿ”’ In the app
The mean of the analysts' 12-month price targets.
Upside to target๐Ÿ”’ In the app
How far the target sits above or below today's price.
Share rating it a buy๐Ÿ”’ In the app
The share of covering analysts with a buy rating.

What does Dr Reddys Laboratories do and what is it sensitive to?

Dr. Sensitive to: foreign exchange rate risk: Indian rupee appreciation.

Business-model card

FY2026 ยท 61 verified
4Revenue
4Channels
5Regulators
5Reg. dependencies
6Sensitivities
7Costs
5Geographies

Dr. Reddy's Laboratories is a global pharmaceutical company that manufactures and sells prescription generic medications, branded generics, unbranded generics, biosimilars, over-the-counter products, and active pharmaceutical ingredients across 88 countries. The company earns revenue from sales of pharmaceutical products to business partners, healthcare providers, and consumers, supplemented by contract research services and licensing arrangements.

Revenue by segment

year ended March 31, 2026
Global Generics88.9%
PSAI10.5%
Others0.6%

Revenue engine

4 verified
Global Generics segment: unbranded generics, branded generics, and biosimilars
Company manufactures and distributes generic medications, branded generics with market leadership in therapeutic segments, and biosimilars in developed and emerging markets. Portfolio includes prescription generics, OTC products, and APIs with specializations in Oncology, CNS, Pain Management, Gastro-Intestinal, Cardiovascular, Respiratory, Anti-Infectives and Diabetology.
Contract research services and Active Pharmaceutical Ingredients manufacturing
Pharmaceutical services business provides contract research and manufactures APIs to customer specifications, generating revenue from services and incremental value-added products.
Proprietary Products business and Aurigene Oncology Limited (AOL) subsidiary
AOL develops novel and best-in-class therapies in oncology and inflammation through customized drug-discovery collaborations with established companies. Proprietary Products business monetizes differentiated formulations through royalties.
1 more statement
Out-licensing arrangements, milestone payments and royalties
Revenue from product out-licensing agreements consisting of initial up-front payments and subsequent milestone-dependent payments. Non-refundable up-front license fees deferred and recognized over remaining performance obligation period.

Customers & channels

4 verified
Dealers and distributors in pharmaceutical channels (37.7%)
Company sells to 6,673 dealers/distributors representing 37.7% of total sales. Top 10 dealers account for 14.2% of distributor sales. Interpretation: sales through indirect wholesale and retail distribution networks.
Pharmaceutical companies and healthcare providers as customers
Company serves diverse customer base including pharmaceutical companies, healthcare providers, and consumers. Engagement through dedicated platforms such as XCEED and customer service center.
Healthcare professionals (HCPs)
Company engages HCPs through physical and digital channels to update on products, innovations, availability and therapy advances. Engagement aims to advance patient outcomes and address unmet needs.
1 more statement
Patients and consumers
Company reaches patients through assistance programs (financial, lifestyle, education, counseling), disease management initiatives, and marketing channels (print, digital, social media). Customer services support product feedback and adverse effect reporting.

Regulators

5 verified
US Food and Drug Administration (FDA)
Regulates approval of new drug applications. As of March 31, 2026, 75 ANDAs and 2 NDAs pending approval; 44 are Para IV litigation cases and 22 believed to have 'First-to-File' status. 347 cumulative ANDAs and 15 ANDAs filed in FY2026.
Regulatory authorities governing manufacturing and product compliance
Company's manufacturing and R&D conduct in compliance with Current Good Manufacturing Practices (cGMP) and 'Quality by Design' principles. Delay in regulatory approvals or additional regulatory action may impact business, increase remedial costs and affect financials.
Environmental regulatory authorities
Company must comply with environmental laws and regulations. Non-compliance, environmental litigation, or plant shutdowns may severely hamper ability to supply products and create substantial costs affecting consolidated financial position.
2 more statements
Securities and Exchange Board of India (SEBI)
SEBI regulates corporate governance norms for listed companies in India through Listing Obligations and Disclosure Requirements Regulations, 2015. Company complies with all corporate governance norms.
Data privacy and information security regulators
Data privacy is significant risk due to sensitive personal data processing directly or through third parties. Regulatory standards govern information security and cybersecurity compliance across jurisdictions.

Regulatory dependencies

5 verified
Drug approval timelines and FDA ANDA/NDA clearances
Company's ability to launch and commercialize products depends on regulatory approvals. Pending approvals (75 ANDAs and 2 NDAs as of March 31, 2026) directly impact future revenue. Para IV litigation cases and First-to-File status affect market entry timing and competitive position.
Good Manufacturing Practices (cGMP) and Quality by Design compliance
Manufacturing and R&D must comply with cGMP standards and Quality by Design principles. Non-compliance invites regulatory action, delays product approvals, and increases remedial costs that reduce profitability.
Environmental law compliance for manufacturing operations
Company's ability to operate manufacturing facilities depends on compliance with environmental laws and regulations. Plant shutdowns or environmental litigation disrupt supply and create substantial costs affecting financial position and liquidity.
2 more statements
Anti-bribery and anti-corruption regulatory compliance
Company must comply with anti-bribery laws and regulations. Non-compliance may result in substantial penalties, fines, criminal prosecution, and potential debarment from public procurement contracts, affecting access to major customer segments.
Data privacy and information security regulations
Company must comply with evolving data privacy regulations across jurisdictions. Breach or non-compliance may result in loss of sensitive data, unauthorized disclosure affecting business operations and financial position.

Sensitivities

6 verified
Foreign exchange rate risk: Indian rupee appreciation
Significant portion of revenues in foreign currencies (USD, GBP, EUR, RUB) while costs are in INR. Indian rupee appreciation reduces INR-measured revenues. Exchange rate fluctuations have been substantial and may continue.
Commodity price risk: raw material and API costs
Commodity prices for active pharmaceutical ingredients and raw material components fluctuate significantly. Commodity price risk is highest in API business. Cost of raw materials forms largest portion of operating expenses.
Interest rate risk on floating-rate borrowings
Every 10% increase or decrease in floating interest rate (CDI, TIIE) on loans and borrowings affects net profit. For years ended March 31, 2026 and 2025, impact was โ‚น347 and โ‚น271 million respectively.
3 more statements
Geopolitical disruptions and supply chain shocks
West Asia crisis, Red Sea corridor disruptions, and maritime chokepoints affect lead times, freight costs, working capital, cold-chain planning, and availability of critical inputs (APIs, intermediates, excipients, packaging). Higher energy price uncertainty impacts operations.
Global inflation and interest rate movements
Global inflation expected to rise to 4.4% in 2026 before easing to 3.7% in 2027. Rising inflation and interest rates are worsening macroeconomic conditions that impact Company's business, financial position, strategy and milestones.
Pricing pressure and loss of product exclusivity
Global pharmaceutical market faces increasing pricing pressure and loss of exclusivity. Patent expiries and adoption of generics and biosimilars offset growth from innovative therapies. Company must navigate pricing pressure while maintaining margins.

Cost inputs

7 verified
Active Pharmaceutical Ingredients (APIs) and raw materials
Cost of raw materials forms largest portion of Company's operating expenses. Prices are commodity products fluctuating in line with commodity cycles, with API raw materials particularly volatile.
Manufacturing and operational expenses
Operating expenses include consumption of stores and spares (โ‚น10,668 mn in FY2026), carriage outward (โ‚น6,743 mn), power and fuel (โ‚น5,565 mn), and other selling expenses.
Capital expenditures for manufacturing and R&D facilities
Company operates 24 manufacturing facilities and 9 R&D facilities globally. In FY2026, โ‚น23 bn CAPEX incurred. Manufacturing designed with scale, sustainability, and LEAN-led efficiency.
4 more statements
Freight and logistics costs including cold-chain requirements
Carriage outward and freight costs are significant operating expenses (โ‚น6,743 mn in FY2026). Geopolitical disruptions and maritime chokepoints affect freight costs and working capital. Cold-chain planning required for biologics and certain products.
Employee and workforce costs
Company has 27,527 employees globally with 74.4 average training hours per FTE. Spent โ‚น256.21 mn on training and development. Well-being measures represent 1.98% of total revenue.
Advertising and marketing expenses
Advertising expenses were โ‚น5,262 mn in FY2026 (up from โ‚น3,346 mn in FY2025). AI-powered commercial and marketing excellence initiatives advanced including analytics-led micro-market segmentation.
Commission on sales
Commission on sales was โ‚น416 mn in FY2026, a component of cost structure for distribution and dealer networks.

Geographies

5 verified
United States market (35.1%)
Largest revenue market with โ‚น117,892 mn revenue in FY2026 (35.1% of total). Company serves US pharma market through ANDA approvals and FDA-regulated products.
European markets (Germany, UK, Ukraine) (35.4%)
Included in Others category representing โ‚น118,718 mn (35.4% of total) in FY2026. Company operates manufacturing and R&D facilities in UK. Subject to Red Sea disruption risks affecting trade connectivity with Europe.
Emerging Markets segment
Emerging Markets contributed โ‚น1,404 Cr revenue in Q1 FY26 with 18% YoY growth. Includes Russia (50%), CISR (14%), and RoW (36%). Growth driven by volume gains, new launches and favorable forex.
2 more statements
China operations through joint venture
Company operates manufacturing facility through joint venture in China. Serves markets across 88 countries globally with integrated global network of 24 manufacturing and 9 R&D facilities.
Mexico and United Kingdom manufacturing operations
Nine API manufacturing units across India, Mexico, UK and US offer capabilities in general, high-potency and specialized chemistries with backward integration into key intermediates.
Each statement is checked word for word against the FY2026 annual report; the passages are in the app.

What changed recently?

Q1 FY2027 results filed (22 Jul 2026).

Change log

6 entries ยท newest first
  1. Results filedQ1 FY2027 results filed.
  2. Results filedQ4 FY2026 results filed.
  3. Results filedQ3 FY2026 results filed.
  4. Results filedQ2 FY2026 results filed.
  5. Results filedQ1 FY2026 results filed.
  6. Results filedQ4 FY2025 results filed.
Get alerts โ†’Sign in to be told when any of these change.

What this page does not tell you

What could not be judged, and why. Never empty.
  • Models not runFair value, EPV, Graham number, Graham value, Lynch, Owner earnings: no valuation stored.
  • FlagsWATCH on 30 of 30 flags judged; 2 red.
  • Data gapsPEG (vendor), PEG on our 3-year EPS growth, Business quality: not available yet.

What this page rests on

โœ“10 years of annual statements, through FY2026 (Mar-26)โœ“10 quarters of resultsโœ“285 months of month-end prices, adjusted for bonuses and splitsโ—‹no valuation of ours yetโœ“business-model card FY2026 ยท 61 verified

Questions people ask

What is Dr Reddys Laboratories's share price today?

Dr Reddys Laboratories last traded at โ‚น1,229.40 on the NSE, as of 12 Oct 2026, 11:00 pm IST, up 2.7% on the day, down 5.2% over a year. Its 52-week range is โ‚น1,101 to โ‚น1,415. The live price is in the app.

What is Dr Reddys Laboratories's market cap?

Dr Reddys Laboratories's market capitalisation is about โ‚น99,911 crore: what it would cost to buy every share at today's price. That makes it the 16th largest mid cap company we cover.

Is Dr Reddys Laboratories Ltd a large cap, mid cap or small cap?

Dr Reddys Laboratories Ltd (DRREDDY) is a mid cap company in AMFI's classification for Jan-Jun 2026. SEBI's buckets go by rank on six-month average market capitalisation: the top 100 are large caps, 101 to 250 mid caps, the rest small caps.

What is Dr Reddys Laboratories Ltd's P/E ratio?

30.94, vs peers 42.8 ยท 5th of 23. Price divided by last year's earnings per share: how many years of today's profit you pay for.

Is Dr Reddys Laboratories Ltd overvalued?

Cheap, with low confidence: no valuation within 120 days; P/E 30.9 vs peers 42.8 (5th of 23); P/B 3.3 vs peers 7.2 (6th of 25). Cheap for a reason: profit -2.4% a year over 3 years, a negative 5-year return.

How does Dr Reddys Laboratories Ltd make money?

Dr. Reddy's Laboratories is a global pharmaceutical company that manufactures and sells prescription generic medications, branded generics, unbranded generics, biosimilars, over-the-counter products, and active pharmaceutical ingredients across 88 countries. The company earns revenue from sales of pharmaceutical products to business partners, healthcare providers, and consumers, supplemented by contract research services and licensing arrangements.

Who are Dr Reddys Laboratories Ltd's peers?

Compared with 24 Pharmaceuticals: Divis Laboratories Ltd, Torrent Pharmaceuticals Ltd, Zydus Lifesciences Ltd, Laurus Labs Ltd, Cipla Ltd and 19 more. The app shows how they compare on every figure.

Is this investment advice?

No. Valarth is a research and learning tool and is not a SEBI-registered investment adviser or research analyst. The figures come from the company's filings and the exchanges; what to do with them is your call.

How did Dr Reddys Laboratories do last quarter?

Dr Reddys Laboratories reported revenue of โ‚น8,070 Cr, up 3.2% on a year earlier and a net profit of โ‚น436 Cr, down 27.4% in the Jun 2026 quarter.

Who owns Dr Reddys Laboratories?

Dr Reddys Laboratories is held by promoters 26.6%, foreign institutions 32.1%, domestic institutions 31.7%.

Does Dr Reddys Laboratories pay a dividend?

Yes. Dr Reddys Laboratories's dividend yield is 0.64% at the latest price; the last payout was โ‚น8.00 a share, ex-dividend 10 Jul 2026.

What do analysts say about Dr Reddys Laboratories?

36 analysts cover Dr Reddys Laboratories, and the consensus is hold. A consensus is a count of opinions, not a forecast; read it beside the numbers.

Everything on Dr Reddys Laboratories, and 6,621 other companies, with 212 filters and the full peer tables